 GST & indirect tax
GST on Footwear in 2026: The ₹2,500 Rule, HSN Codes, Parts and Worked Invoices
GST on footwear in 2026: 5% on shoes and chappals up to ₹2,500 a pair, 18% above, HSN 6401–6406, shoe parts, discounts, inverted-duty refunds and worked ₹ bills.
 Edited by Sumeet YadavFounder & editor, MSMETOOLS · fact-checked against official sources
Contents (10)
- 1. GST rates on footwear in 2026
- 2. How the ₹2,500 per pair test works
- 3. HSN codes for footwear
- 4. What changed on 22 September 2025
- 5. Worked invoices: GST on footwear in rupees
- 6. Shoe parts, materials and job work
- 7. Inverted duty and refunds for footwear makers
- 8. Retailers, online sellers and small shops
- 9. Common mistakes with GST on footwear
- 10. What to do next
Footwear was one of the clearest winners of GST 2.0. Most shoes, sandals and chappals that Indians buy now carry the lowest standard rate, but the tax still turns on a single number — the price per pair — and on what exactly is being sold. This guide is for shoe retailers, wholesalers, manufacturers in Agra, Kanpur, Ambur, Kolhapur and Bahadurgarh, online sellers, and buyers who want to check a bill. It covers the 2026 rates, how the ₹2,500 test works with discounts and inclusive prices, the HSN codes, shoe parts and job work, inverted-duty refunds and worked invoices in rupees. Rates were checked against the notified schedule in October 2026.
Quick answer
Footwear of sale value up to ₹2,500 per pair attracts 5% GST; footwear above ₹2,500 a pair attracts 18%. This applies from 22 September 2025 to every heading from 6401 to 6405 — leather, rubber, plastic and canvas alike. The limit is tested on the price before GST, per pair. Parts of footwear (6406) are 18% at any price.
A ₹1,999 pair of sneakers: GST ₹99.95 at 5%
A ₹3,999 pair of leather shoes: GST ₹719.82 at 18%
Invoice discounts count; later credit-note discounts don't change the rate
Before 22 Sep 2025: 12% up to ₹1,000, 18% above
No compensation cess on footwear
GST rates on footwear in 2026
Notification 9/2025–Central Tax (Rate), which replaced the 2017 goods schedule on 22 September 2025, deals with footwear in two places. Schedule I, the 2.5% central tax schedule, has serial 392: "Footwear of sale value not exceeding Rs.2500 per pair", against the whole of Chapter 64. Schedule II, the 9% central tax schedule, lists headings 6401 to 6405 at serials 202 to 206 without any price condition, and parts of footwear under 6406 at serial 207. Read together, a complete pair priced up to ₹2,500 falls in the specific 2.5% entry, so it carries 5% in all (CGST plus SGST, or the same as IGST between states). Anything above the limit, and every part, stays in the 9% schedule at 18%.
The 56th GST Council's footwear annexure records this as two moves: footwear up to ₹2,500 a pair went "12% to 5%", and footwear above ₹2,500 a pair was "maintained at 18%" with a change in the value line. In practice the change was larger than the headline suggests. Pairs between ₹1,001 and ₹2,500 — the bulk of branded school shoes, sports shoes and office shoes — were at 18% before, and dropped straight to 5%.
GST on footwear and related goods (2026)
| Product (HSN) | GST rate | Schedule entry |
|---|---|---|
Any footwear of Chapter 64, sale value up to ₹2,500 a pair | 5% | Sch. I 392 |
Waterproof moulded rubber/plastic footwear above ₹2,500 (6401) | 18% | Sch. II 202 |
Rubber or plastic sole and upper — slides, PVC sandals, many sports shoes — above ₹2,500 (6402) | 18% | Sch. II 203 |
Leather-upper shoes, boots, sandals above ₹2,500 (6403) | 18% | Sch. II 204 |
Textile-upper shoes — canvas, knit sneakers — above ₹2,500 (6404) | 18% | Sch. II 205 |
Other footwear above ₹2,500 (6405) | 18% | Sch. II 206 |
Parts — uppers, insoles, heel cushions, gaiters (6406) | 18% | Sch. II 207 |
Orthopaedic footwear (9021) | 5% | Sch. I 486 |
Finished leather (4107, 4112, 4113) | 5% | Sch. I 284–286 |
PVC/PU coated fabric — 'rexine', synthetic leather (5903) | 5% | Sch. I 378 |
Any footwear of Chapter 64, sale value up to ₹2,500 a pair
- GST rate
5%
- Schedule entry
Sch. I 392
Waterproof moulded rubber/plastic footwear above ₹2,500 (6401)
- GST rate
18%
- Schedule entry
Sch. II 202
Rubber or plastic sole and upper — slides, PVC sandals, many sports shoes — above ₹2,500 (6402)
- GST rate
18%
- Schedule entry
Sch. II 203
Leather-upper shoes, boots, sandals above ₹2,500 (6403)
- GST rate
18%
- Schedule entry
Sch. II 204
Textile-upper shoes — canvas, knit sneakers — above ₹2,500 (6404)
- GST rate
18%
- Schedule entry
Sch. II 205
Other footwear above ₹2,500 (6405)
- GST rate
18%
- Schedule entry
Sch. II 206
Parts — uppers, insoles, heel cushions, gaiters (6406)
- GST rate
18%
- Schedule entry
Sch. II 207
Orthopaedic footwear (9021)
- GST rate
5%
- Schedule entry
Sch. I 486
Finished leather (4107, 4112, 4113)
- GST rate
5%
- Schedule entry
Sch. I 284–286
PVC/PU coated fabric — 'rexine', synthetic leather (5903)
- GST rate
5%
- Schedule entry
Sch. I 378
There is no compensation cess on footwear, so the rate on the invoice is the whole tax. Orthopaedic footwear made for a medical condition is excluded from Chapter 64 by its chapter notes and is classified with orthopaedic appliances under 9021, at 5% irrespective of price. A regular "comfort" shoe with a cushioned insole is not orthopaedic footwear; the 9021 entry needs footwear made to correct or support a disorder.
How the ₹2,500 per pair test works
The words in the notification are "sale value not exceeding Rs.2500 per pair". Four practical points follow from that wording and from section 15 of the CGST Act.
It is the price before tax. The sale value is the transaction value on which GST is charged, so you test the taxable value, not the amount the customer pays. A pair sold at ₹2,500 plus ₹125 GST, ₹2,625 in all, is at 5%. A pair at ₹2,501 plus 18% is ₹2,951.18.
It is not the MRP. Footwear is sold under the Legal Metrology rules with an MRP on the box, but the GST test looks at the actual price charged. A pair with an MRP of ₹3,499 that a retailer sells for ₹2,400 before tax is at 5%. The same pair sold at full MRP is at 18%.
Invoice discounts count; credit notes don't change the rate. Section 15(3)(a) excludes a discount given before or at the time of supply and recorded on the invoice. Section 15(3)(b) allows a later discount to reduce the value only if it was agreed in advance and the input credit is reversed by the buyer, and it is passed through a credit note. The rate is fixed when the invoice is issued, so a later credit note reduces the tax but does not move the pair into the lower slab.
It is per pair. A "buy two for ₹4,000" offer is two pairs at ₹2,000 each, and each is at 5%. A single pair bundled with socks or a shoe-care kit for one price needs care: if the footwear is the principal supply, the whole bundle takes the footwear rate, so the bundle price per pair decides the slab. Show the pair and the free item clearly on the invoice.
The GST-inclusive "dead zone"
Many shops display one all-inclusive price. That works cleanly up to ₹2,625 — which is ₹2,500 plus 5% — and from ₹2,950.01 upwards, which is more than ₹2,500 plus 18%. Between those two figures, neither rate fits. A pair tagged at ₹2,800 including tax would have a value of ₹2,666.67 if the tax were 5%, which is above the limit, so 18% should apply; but at 18% its value is only ₹2,372.88, which is below the limit, so 5% should apply. We found no CBIC clarification on this band. The safe course is to keep inclusive prices at or below ₹2,625, or above ₹2,950, or to quote such pairs on a pre-tax basis so the rate is unambiguous.
HSN codes for footwear
Chapter 64 of the Customs Tariff is organised by the material of the outer sole and of the upper. The rate does not depend on the heading (except for parts), but you must still report the correct HSN in your invoices and in Table 12 of GSTR-1 — at least a 4-digit HSN code if your aggregate turnover is up to ₹5 crore and a 6-digit HSN code above that.
| HSN | What it covers | Typical products |
|---|---|---|
| 6401 | Waterproof footwear, rubber or plastic sole and upper, upper not stitched or riveted to the sole | Gumboots, moulded PVC rain boots |
| 6402 | Other footwear with rubber or plastic soles and uppers | Hawai chappals, slides, PVC and EVA sandals, many synthetic sports shoes |
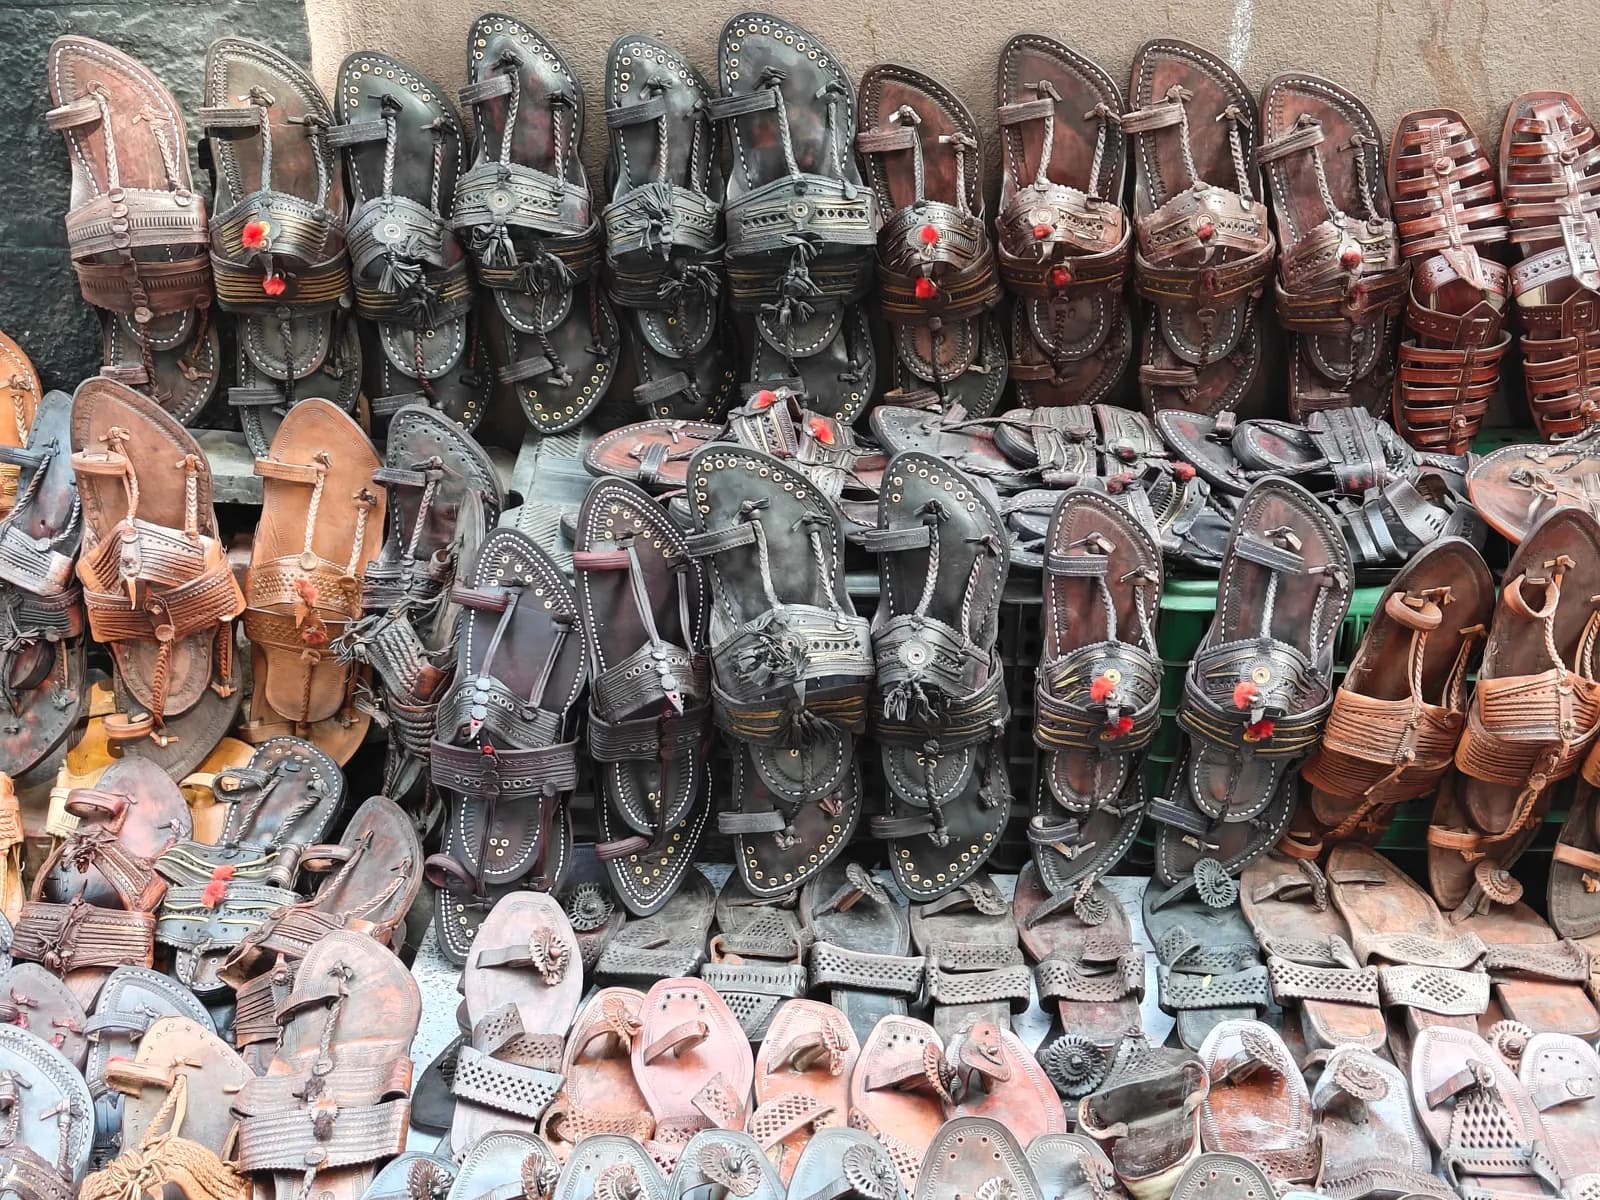
| 6403 | Rubber, plastic, leather or composition-leather sole with a leather upper | Leather shoes, Kolhapuri chappals, leather sandals and boots |
| 6404 | Rubber, plastic, leather or composition-leather sole with a textile upper | Canvas shoes, knit running shoes, cloth jootis with rubber soles |
| 6405 | Other footwear | Footwear with uppers of other materials, such as cork or jute |
| 6406 | Parts of footwear | Uppers, insoles, heel cushions, gaiters, leggings |
Where an upper uses more than one material — leather panels on a mesh shoe, for example — the Chapter notes classify it by the material with the greatest external surface area. That matters for your HSN reporting, not for the rate. Our HSN code guide and the HSN code finder help with unusual items.
What changed on 22 September 2025
Footwear has had a price-based split since GST began, but the line and the rates have moved twice. From 1 January 2022, Notification 21/2021–Central Tax (Rate) put "footwear of sale value not exceeding Rs.1000 per pair" in the 6% central tax schedule, which made it 12% in all; before that date, footwear in this band was taxed at 5%. Footwear above ₹1,000 a pair stayed at 18%.
GST 2.0 raised the line to ₹2,500 and cut the lower rate to 5%, with effect from 22 September 2025. The upper rate stayed at 18%.
For stock on hand on 22 September 2025, the rate is decided by the time of supply. An invoice raised on or after that date takes the new rate, even if the goods were bought earlier at higher tax. Retailers who had paid 18% on ₹1,800 shoes bought before the change kept the credit and now charge 5% on sale, which is why many footwear sellers started building up unused credit in late 2025. As of October 2026, no later change to footwear rates has been notified; a recommendation from a GST Council meeting takes effect only once a rate notification is issued.
Worked invoices: GST on footwear in rupees
The prices below are illustrative round figures to show the arithmetic, not market quotes.
| Pair (illustrative) | Taxable value | GST rate | GST | Bill total |
|---|---|---|---|---|
| Rubber hawai slippers | ₹249 | 5% | ₹12.45 | ₹261.45 |
| School shoes | ₹899 | 5% | ₹44.95 | ₹943.95 |
| Running shoes | ₹1,999 | 5% | ₹99.95 | ₹2,098.95 |
| Leather office shoes | ₹2,500 | 5% | ₹125.00 | ₹2,625.00 |
| Leather office shoes | ₹2,501 | 18% | ₹450.18 | ₹2,951.18 |
| Leather boots | ₹3,999 | 18% | ₹719.82 | ₹4,718.82 |
The jump at ₹2,500 is sharp. One rupee more of price adds ₹325 of tax, which is why many brands now price pairs at ₹2,499 or ₹2,500 before GST.
A discount at the till. A sneaker with a list price of ₹3,200 is sold in a sale at 25% off, and the shop's invoice shows ₹3,200 less ₹800 discount. The taxable value is ₹2,400 and the rate is 5%, so GST is ₹120 and the customer pays ₹2,520. If instead the shop billed ₹3,200 at 18% (₹576 GST) and later issued a credit note for ₹800, the credit note would reverse ₹144 of tax at the original 18%. The final tax would be ₹432 on the same ₹2,400 — ₹312 more than billing the discount on the invoice.
A wholesale bill. A distributor in Agra sells 200 pairs of school shoes to a retailer in Lucknow at ₹650 a pair. The value is ₹1,30,000, the supply is between states, and IGST at 5% is ₹6,500. The consignment exceeds ₹50,000, so it needs an e-way bill. The ₹2,500 test is applied to the price per pair on this invoice — ₹650 — not to the retailer's later selling price.
Try it — GST on a pair of shoes
Shoe parts, materials and job work
The ₹2,500 rule applies only to complete footwear. A unit that sells uppers to a shoe assembler, or a supplier of moulded soles, removable insoles or heel counters, bills under 6406 at 18% whatever the price. Outer soles made of rubber are usually classified with rubber articles under 4016, also at 18%, and footwear adhesives under 3506 are 18%.
Some key materials are cheaper. Leather further prepared after tanning or crusting — the finished leather that shoe makers cut — fell from 12% to 5% under GST 2.0, which helps the Agra, Kanpur and Tamil Nadu leather clusters. PVC and PU coated fabrics of heading 5903, which the trade calls rexine or synthetic leather, are 5%. Laces, eyelets, buckles, zips, EVA and PU sheets and packaging cartons follow their own headings, and most are at 18%.
Job work. Many footwear units send uppers for stitching, or soles for moulding, to small job workers. The PIB FAQs on the 56th Council say the new 5% rate for job work on hides, skins and leather of Chapter 41 does not cover job work for leather goods or footwear of Chapters 42 and 64. Footwear job work therefore falls on the residuary job-work entry, which the same FAQs say moved from 12% to 18% (9% CGST + 9% SGST, or 18% IGST). A job worker stitching ₹2,00,000 of uppers in a month bills ₹36,000 of GST, which the principal can claim as credit. Our GST on job work guide covers the challan and ITC-04 rules.
Inverted duty and refunds for footwear makers
A manufacturer whose output is mostly at 5% but whose soling compounds, adhesives, parts, packaging and job work are at 18% pays more GST on inputs than it collects on sales. That excess credit sits in the electronic credit ledger unless it is refunded. Section 54(3) of the CGST Act allows a refund of credit accumulated because the rate on inputs is higher than the rate on output supplies, and footwear is not among the goods on which such refunds are barred.
The refund is capped by the formula in Rule 89(5). Maximum refund equals the turnover of the inverted-rated supply multiplied by Net ITC and divided by adjusted total turnover, minus the tax payable on that inverted supply multiplied by Net ITC and divided by the ITC availed on inputs and input services. "Net ITC" counts only inputs — not input services and not capital goods — so credit on job work, freight and rent is never refunded.
A worked month. A sandal maker in Bahadurgarh sells ₹40,00,000 of pairs priced below ₹2,500, all at 5%, so its output tax is ₹2,00,000. Its credit for the month is ₹2,70,000 on ₹15,00,000 of 18% inputs (soling sheets, adhesives, parts), ₹40,000 on ₹8,00,000 of 5% coated fabric, and ₹54,000 on ₹3,00,000 of 18% services — ₹3,64,000 in all. The excess over output tax is ₹1,64,000.
Using Rule 89(5): Net ITC is ₹3,10,000 (inputs only). The first part is ₹40,00,000 × ₹3,10,000 ÷ ₹40,00,000 = ₹3,10,000. The second part is ₹2,00,000 × ₹3,10,000 ÷ ₹3,64,000 ≈ ₹1,70,330. The maximum refund is about ₹1,39,670. The remaining ₹24,330 or so — the service share — stays in the ledger and can only be used against future output tax.
The sandal maker's month (illustrative)
₹2,00,000
Output GST at 5%
₹3,64,000
Total ITC for the month
≈ ₹1,39,670
Maximum inverted-duty refund
Rule 89(5)
90%
Provisional refund on risk assessment
claims from 1 Oct 2025
Refund claims are filed in FORM GST RFD-01 on the GST portal, for one or more tax periods, within two years from the relevant date of the relevant date. CBIC's Instruction 06/2025-GST asked officers to sanction 90% provisionally, on the system's risk assessment, for inverted-duty claims filed from 1 October 2025. Makers with a mix of pairs above and below ₹2,500 have a smaller inverted share, because their 18% sales absorb more of the credit.
Retailers, online sellers and small shops
Registration. A footwear shop must register once its aggregate turnover crosses ₹40 lakh in most states, or ₹20 lakh in the states that did not adopt the higher limit for goods. Selling between states, or through an e-commerce marketplace, generally requires registration regardless of turnover.
Composition. A shop with turnover up to ₹1.5 crore can opt for the composition scheme and pay 1% of turnover instead of charging GST. It cannot collect tax from customers or claim input credit. Now that most footwear is at 5% with credit, many shoe shops that sell mostly to consumers compare their purchase credit with the 1% cost before deciding. Our composition scheme guide shows the arithmetic.
Online marketplaces. An e-commerce operator collects tax at source of 0.5% (0.25% CGST + 0.25% SGST, or 0.5% IGST) of the net value of taxable supplies made through it, and the seller can claim that amount in its cash ledger. The 5% or 18% test is applied to the seller's own sale price per pair, after any discount the seller funds and shows on the invoice. A platform-funded coupon that the seller does not account for as its own discount does not change the seller's invoice value.
Exports. Footwear exported under a letter of undertaking is zero-rated, so no IGST is paid and credit can be refunded. See our guide to the LUT in GST.
Common mistakes with GST on footwear
Check your footwear invoice
0/7Testing the MRP instead of the selling price. The notification uses sale value. A pair with an MRP above ₹2,500 sold at a lower price is at 5%; a pair with a lower MRP that is sold with paid add-ons may cross the limit.
Testing the GST-inclusive price. A pair billed at ₹2,550 including tax is ₹2,428.57 plus 5%, which is correct. Billing it as ₹2,161.02 plus 18% overcharges the customer and is wrong.
Giving end-of-season discounts only by credit note. The tax falls, but the 18% rate on the original invoice stays. If the discount is known at the time of sale, put it on the invoice.
Charging 5% on shoe parts. Uppers, insoles and heel cushions are parts under 6406 and are 18% even when they are cheap.
Charging 5% on footwear job work. The 5% leather job-work rate covers Chapter 41 leather only. Stitching uppers or moulding soles for a footwear brand is residuary job work at 18% (9% CGST + 9% SGST, or 18% IGST).
Not filing inverted-duty refunds. Small makers often let excess credit pile up. A refund claim filed regularly releases working capital, and the two-year time limit runs from the end of the relevant tax period.
Official links
- Notification 9/2025–CT(Rate) — goods rate scheduleFootwear Sch. I 392; Sch. II 202–207
- 56th GST Council — recommendations and annexuresFootwear sector changes
- PIB FAQs on the 56th GST CouncilJob work for footwear
- Section 15, CGST ActDiscounts and value
- Rule 89, CGST RulesInverted-duty refund formula
- CGST rate notificationsLater amendments, if any
What to do next
If you sell footwear, update your billing software so the rate is chosen from the price per pair after discount, and check that every product is mapped to the right heading. If you make footwear, run the Rule 89(5) formula on last quarter's figures to see how much refund you can claim. Use the GST calculator to check any bill and the invoice generator to issue one, and read our guides to GST on garments, GST 2.0 and input tax credit.
This is general information, not legal or tax advice — confirm on the official source or with a professional.
Frequently asked questions
From 22 September 2025, footwear of sale value up to ₹2,500 per pair attracts 5% GST, and footwear above that value attracts 18%. Before GST 2.0 the dividing line was ₹1,000 a pair, with 12% below it and 18% above. So pairs between ₹1,001 and ₹2,500 fell from 18% to 5%, and cheap pairs from 12% to 5%.
Before GST. The test uses the sale value per pair, which is the transaction value on which tax is charged, not the MRP printed on the box and not the GST-inclusive price. A pair sold at ₹2,500 plus 5% GST, ₹2,625 in all, stays at 5%. A pair sold at ₹2,501 before tax moves to 18%.
Footwear is in Chapter 64. Shoes with rubber or plastic soles and uppers are 6402, shoes with leather uppers 6403, shoes with textile uppers such as canvas and most knit sneakers 6404, waterproof moulded rubber or plastic footwear 6401 and other footwear 6405. Parts of footwear, including uppers and insoles, are 6406. The rate depends on price per pair, not on the heading, except for parts.
Parts of footwear under heading 6406, such as uppers, removable insoles, heel cushions and gaiters, attract 18% whatever their price. The ₹2,500 rule applies only to complete footwear. Finished leather is 5% and PVC or PU coated fabric is 5%, while rubber soling, adhesives and most chemicals are 18%.
It can. A discount given before or at the time of sale and shown on the invoice is excluded from the value under section 15(3)(a) of the CGST Act. If the discounted price is ₹2,500 or less a pair, the 5% rate applies. A discount given later through a credit note reduces the value but does not change the rate on the original invoice.
Yes. A maker selling mostly at 5% while buying soling, adhesives and parts at 18% builds up credit, and section 54(3) allows a refund of that inverted-duty credit using the Rule 89(5) formula. The formula counts inputs but not input services or capital goods. Since October 2025, 90% can be released provisionally on risk assessment.
Sources & verification
Figures on this page were checked against the sources below when it was last reviewed on 9 October 2026. Each rate and limit is stored once with its own official source and review date, and official update channels are monitored daily so changes are picked up. How we verify
- 1.Notification No. 9/2025–Central Tax (Rate), 17 September 2025 (Gazette of India, G.S.R. 641(E)) — Ministry of Finance / Gazette of India · accessed 9 October 2026
- 2.Recommendations of the 56th GST Council meeting (press release with rate annexures) — GST Council / PIB · accessed 9 October 2026
- 3.FAQs on the decisions of the 56th GST Council (PIB, 3 September 2025) — PIB / Ministry of Finance · accessed 9 October 2026
- 4.West Bengal Notification 40-F.T. (10 January 2022) — corresponding to Notification 21/2021-Central Tax (Rate) — Finance Department, Government of West Bengal (state mirror) · accessed 9 October 2026
- 5.Section 15 – CGST Act, 2017 (value of supply) — CBIC · accessed 9 October 2026
- 6.Rule 89 – CGST Rules, 2017 (refund applications and inverted-duty formula) — CBIC · accessed 9 October 2026
- 7.CBIC instruction on 90% provisional refunds (summary of Instruction 06/2025-GST) — VJM & Associates (secondary) · accessed 9 October 2026
MSMETOOLS is an independent platform and is not affiliated with any government agency, ministry or department.
Tools for this
GST Calculator (India)
Calculate GST for your sales and purchases with current rates.
Invoice Generator
Create professional invoices with tax, logo and custom details.
HSN Code Finder (India)
Find the correct HSN/SAC code for your product.
Related guides
 GST on Garments 2026: 5% vs 18%, ₹2,500 Rule & HSN CodesRead guide
 GST on Gold 2026: 3% Rate, Making Charges & Old Gold RulesRead guide
 GST on Bicycle 2026: 5% on Cycles, Parts & E-Bikes, HSN 8712Read guide
 GST on Fertilizers 2026: Urea, DAP, Organic & Inputs RatesRead guide
Official links open the government site in a new tab.