 Finance & accounting
Short-Term Business Loans in 2026: Terms, Payments, Factor Rates and the Real APR
How short-term business loans work in 2026: terms, daily and weekly payments, converting factor rates to APR, state disclosure laws and a worked $40,000 example.
 Edited by Sumeet YadavFounder & editor, MSMETOOLS · fact-checked against official sources
Contents (10)
- 1. What counts as a short-term business loan
- 2. Daily and weekly payments: what they do to cash flow
- 3. Factor rates and how to convert them to APR
- 4. Worked example: a $40,000 inventory build
- 5. Short-term loan vs line of credit vs other options
- 6. When a short-term loan actually makes sense
- 7. State disclosure and registration laws
- 8. Renewals, stacking and other traps
- 9. How to qualify and apply
- 10. What to do next
Short-term business loans are built for speed: money in your account within days, repaid over a few months through automatic daily or weekly debits. That speed is useful when a supplier discount, a seasonal stock-up or a gap between a big job and the customer's payment won't wait for a bank. It's also expensive, and the way these loans are priced, often as a factor rate rather than an interest rate, makes the cost easy to underestimate. This guide covers typical terms, how frequent payments affect your cash flow, how to convert a factor rate into an APR, the SBA's short-term options, the state laws that now require cost disclosures, and a worked $40,000 example. Figures were checked in October 2026.
Quick answer
A short-term business loan is a lump sum repaid over roughly 3 to 18 months, usually through daily or weekly automatic debits. Many are priced with a factor rate (for example 1.30, meaning $1.30 repaid per $1 borrowed) instead of an interest rate, so the real annual cost depends on how fast you repay. A 1.30 factor over six months works out to over 100% APR.
Terms of 3–18 months are typical; no legal definition exists
Convert factor rates and fees to an APR before comparing offers
A line of credit or SBA CAPLines usually costs far less for seasonal needs
SBA charges just 0.25% of the guaranteed portion upfront on 7(a) loans of 12 months or less (FY2027)
New York, California, Texas and several other states require cost disclosures
What counts as a short-term business loan
There's no statutory definition. In practice, lenders use "short-term" for business financing repaid within about a year to eighteen months, and online lenders commonly offer terms of three to twelve months. Banks make short-term loans too, typically a 90-day to 12-month note for a specific purpose, such as buying inventory ahead of a busy season, with a single repayment or monthly payments.
What sets most online short-term loans apart is not just the length. It's the combination of:
- Fast approval, often within one or two business days, based largely on bank account data
- Automatic debits from your business checking account every business day or once a week
- Fixed-fee pricing quoted as a factor rate or a flat finance charge, rather than an annual interest rate
- Small amounts, commonly from a few thousand dollars to the low six figures
Short-term loans sit next to several similar products. A merchant cash advance buys a share of your future card or bank receipts rather than lending money, and repayments may float with sales; our merchant cash advance guide covers it in depth. Invoice factoring sells unpaid invoices for an immediate advance. A line of credit lets you draw and repay repeatedly. All of these are used to fund working capital, and all should be compared on the same basis: total cost and APR.
Demand is broad. In the Federal Reserve Banks' 2025 Small Business Credit Survey, 38% of employer firms applied for a loan, line of credit or merchant cash advance in the previous year, and the most common reason for seeking financing was meeting operating expenses. Only 42% of applicants received the full amount they sought, which is one reason fast online products have grown.
Daily and weekly payments: what they do to cash flow
Frequent payments are the feature owners most often underestimate. A loan with a $412 daily debit doesn't feel large on any single day, but over a month of about 21 business days it's roughly $8,670. If your revenue is lumpy, say a contractor paid in large invoices every few weeks, the account can run short between receipts, and a returned debit can trigger fees or a default.
Weekly debits are easier to plan around but still pull cash out faster than a monthly bank payment. Before you sign, map the payments against your actual deposit pattern for the past three to six months. Ask:
- On which days will the debit hit, and what happens if it falls on a holiday?
- What fee is charged for a returned or rejected debit, and how many returns count as a default?
- Can you switch from daily to weekly payments, and does that change the price?
- Can you pause or reduce payments if sales fall, as some revenue-based products allow?
Texas's 2025 commercial sales-based financing law limits automatic debits: a provider or broker can't set up automatic debits from your deposit account unless it holds a perfected, first-priority security interest in that account. The Federal Trade Commission has also brought cases against short-term financing providers for withdrawing more than borrowers authorized, including a $9.8 million settlement with Yellowstone Capital in 2021. Keep records of every debit and compare them with the contract.
Factor rates and how to convert them to APR
A factor rate is a multiplier: borrow $40,000 at a factor of 1.30 and you repay $52,000. The $12,000 difference is fixed when you sign, whether you repay over four months or twelve. That's why a factor rate can't be compared directly with an interest rate. A 1.30 factor sounds like 30%, but if you repay over six months, you're paying that cost on a balance that declines every day, for half a year.
An APR expresses the cost per year on the money you actually have. To convert:
- Work out the total repayment: amount × factor rate.
- Divide by the number of payments to get each payment.
- Subtract any upfront fees from the amount to get the cash you actually receive.
- Find the periodic rate at which the payments repay that cash (a spreadsheet's
RATE(n, -payment, cash received)does this). - Multiply the periodic rate by the number of payment periods in a year (about 252 business days for daily, 52 for weekly).
| Offer on $40,000 | Total repaid | Payment | Approx. APR |
|---|---|---|---|
| Factor 1.30, 6 months, daily, no fee | $52,000 | $412.70 × 126 | 109% |
| Factor 1.30, 6 months, daily, 3% fee | $52,000 | $412.70 × 126 | 123% |
| Factor 1.30, 6 months, weekly, 3% fee | $52,000 | $2,000 × 26 | 120% |
| Factor 1.30, 12 months, weekly, 3% fee | $52,000 | $1,000 × 52 | 61% |
| Factor 1.20, 12 months, weekly, no fee | $48,000 | $923 × 52 | 37% |
The pattern is consistent: the shorter the term, the higher the APR for the same factor rate, and upfront fees push it higher still because you receive less cash but repay the same amount. These figures are our own calculations from the stated terms, not lender quotes.
Several states now make lenders do this math for you. New York's Commercial Finance Disclosure Law requires covered providers to disclose an estimated APR, the total repayment, the payment amounts and frequency, the estimated term and the cost of paying off early on offers up to $2.5 million. California's rules, enforced by the Department of Financial Protection and Innovation, require similar disclosures, including an estimated APR, on commercial financing of $500,000 or less.
Worked example: a $40,000 inventory build
A garden center does 60% of its sales between March and June. In February it needs $40,000 to stock up on plants and supplies, and expects to sell through by early summer. It compares three options.
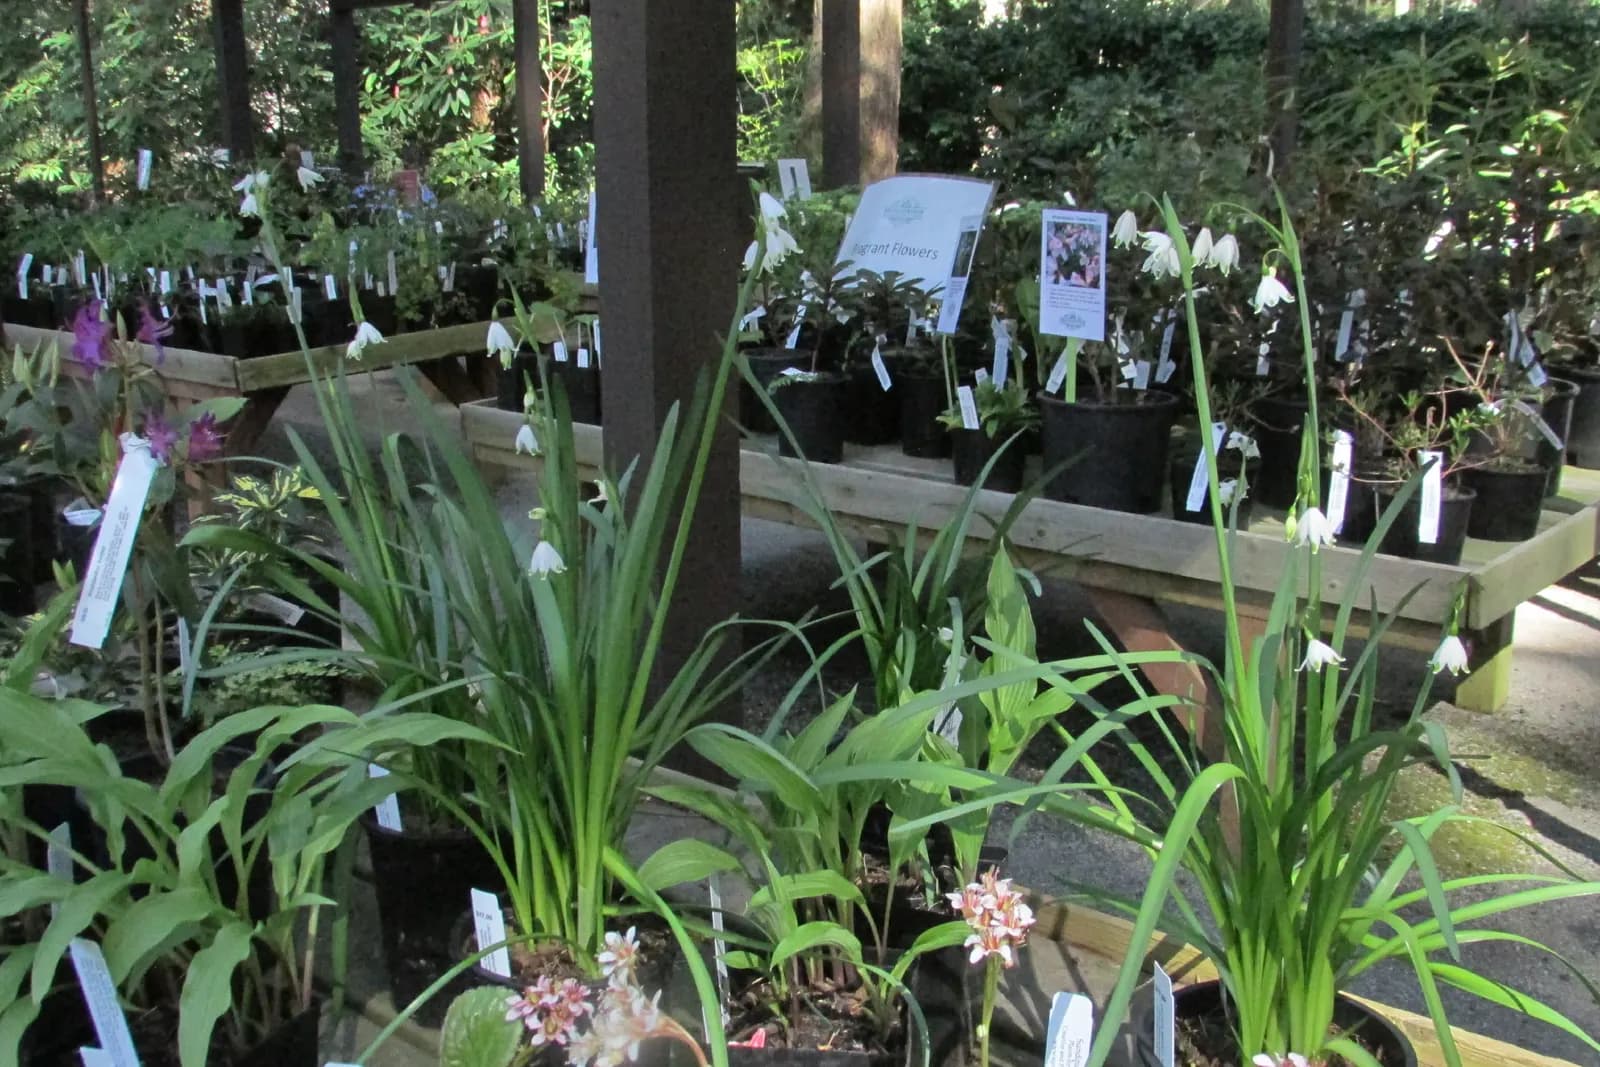
Option A: online short-term loan. $40,000 at a factor of 1.30 over six months, daily debits, with a 3% origination fee deducted. The business receives $38,800 and repays $52,000 in 126 daily payments of $412.70. Total cost: $13,200. APR: about 123%. The daily debits start immediately, in February, months before the spring sales arrive.
Option B: 12-month bank term loan. If the bank approves $40,000 for 12 months at 15% with monthly payments, each payment is about $3,610 and total interest is about $3,320. Approval takes longer and needs financial statements and tax returns.
Option C: bank line of credit. The business draws $40,000 in February at an assumed 12% (prime of 7.00% plus 5%), then repays from spring sales so that the average balance over six months is about $20,000. Interest is roughly $20,000 × 12% × ½ = $1,200, plus any annual or draw fees.
Cost of the same $40,000 seasonal need
$13,200
Short-term loan, 1.30 factor
~123% APR with a 3% fee
$3,320
12-month bank loan at 15%
monthly payments
~$1,200
Line of credit at 12%
repaid from spring sales
0.25% of the guaranteed portion
SBA upfront fee, ≤12-month loans
FY2027
The short-term loan costs about ten times as much as the line of credit here, mostly because its cost is fixed regardless of how quickly the inventory sells and because payments begin before revenue does. The online loan's advantage is speed and approval odds. If the garden center has time, a bank line or an SBA CAPLines seasonal line is the better tool. Model your own cash cycle with the working capital calculator.
Short-term loan vs line of credit vs other options
Short-term financing options compared
| Online short-term loan | Bank line of credit | SBA CAPLines / Express line | Merchant cash advance | |
|---|---|---|---|---|
Typical term | 3–18 months | 12 months, renewable | Up to 10 years | Until the purchased receipts are paid |
Payments | Daily or weekly | Monthly interest; repay as you collect | Monthly; per line structure | Daily or weekly share of sales |
Pricing | Factor rate or flat fee | Prime + margin | Prime + margin, SBA-capped | Factor rate |
Speed | 1–3 days | Weeks | Weeks | 1–3 days |
Early payoff saves money? | Only if contract allows | Yes | Yes | Rarely |
Best for | Urgent, quick-return needs | Seasonal and uneven needs | Seasonal, contract and inventory cycles | Last resort |
Typical term
- Online short-term loan
3–18 months
- Bank line of credit
12 months, renewable
- SBA CAPLines / Express line
Up to 10 years
- Merchant cash advance
Until the purchased receipts are paid
Payments
- Online short-term loan
Daily or weekly
- Bank line of credit
Monthly interest; repay as you collect
- SBA CAPLines / Express line
Monthly; per line structure
- Merchant cash advance
Daily or weekly share of sales
Pricing
- Online short-term loan
Factor rate or flat fee
- Bank line of credit
Prime + margin
- SBA CAPLines / Express line
Prime + margin, SBA-capped
- Merchant cash advance
Factor rate
Speed
- Online short-term loan
1–3 days
- Bank line of credit
Weeks
- SBA CAPLines / Express line
Weeks
- Merchant cash advance
1–3 days
Early payoff saves money?
- Online short-term loan
Only if contract allows
- Bank line of credit
Yes
- SBA CAPLines / Express line
Yes
- Merchant cash advance
Rarely
Best for
- Online short-term loan
Urgent, quick-return needs
- Bank line of credit
Seasonal and uneven needs
- SBA CAPLines / Express line
Seasonal, contract and inventory cycles
- Merchant cash advance
Last resort
Choose a line of credit when the need repeats or the amount varies: seasonal inventory, payroll gaps, waiting on customer invoices. You pay interest only on what you use. Our business line of credit guide explains bank and SBA lines.
Choose a short-term loan when you need a known sum quickly for something that pays back fast and predictably, and you can absorb the payment schedule from existing cash flow.
Consider SBA options if you have a few weeks. SBA's CAPLines program offers seasonal, contract, builders and working capital lines, and SBA Express can be set up as a revolving line. For FY2027, SBA's upfront guaranty fee on 7(a) loans with a maturity of 12 months or less is only 0.25% of the guaranteed portion, so a $100,000 Express line for 12 months with its 50% guaranty carries a fee of about $125. Rates are capped at prime plus 3% to 6.5% depending on size; see our SBA loan rates guide.
Consider invoice financing if the gap is caused by slow-paying business customers. Invoice factoring advances cash against specific invoices instead of your general credit.
When a short-term loan actually makes sense
High cost doesn't automatically make a short-term loan a bad decision. It makes sense when three things are true. First, the money earns a return that clearly beats the cost within the term: a supplier offering 15% off a bulk order you'll sell within eight weeks, or a contract that pays on delivery. Second, the cash to repay already exists in your pattern of deposits, so the debits don't depend on the new sales arriving on time. Third, a cheaper option isn't available in the time you have.
It rarely makes sense to cover payroll or rent during a sustained drop in sales, to refinance another short-term product, or to fund equipment or a remodel that pays back over years. In those cases the frequent payments drain the cash the business needs to recover.
The market data supports caution. In the Federal Reserve's 2025 survey, 60% of businesses that borrowed from online lenders said the actual cost was higher than they had expected, and high interest rates and unfavorable repayment terms were the most commonly reported problems with those lenders. At the same time, banks are lending more on lines: the Kansas City Fed's survey found new small business credit line balances up about 21% year over year in the second quarter of 2026, so it's worth asking your bank before assuming it will say no.
State disclosure and registration laws
There's no federal law capping the cost of business loans, and the federal Truth in Lending Act applies to consumer credit, not business credit. States have stepped in with disclosure laws, most aimed at non-bank providers. Banks are generally exempt.
State commercial financing disclosure laws
Jul 1, 2022
Virginia — sales-based financing disclosures and registration
Dec 9, 2022
California — DFPI disclosures for financing of $500,000 or less
Jan 1, 2023
Utah — registration and disclosure act
Jul 1, 2023
Florida — commercial financing disclosure law
Aug 1, 2023
New York — disclosures up to $2.5 million
Jan 1, 2024
Georgia — disclosures for financing of $500,000 or less
Jul 1, 2024
Connecticut and Kansas
Feb 28, 2025
Missouri
Sep 1, 2025
Texas — HB 700 disclosures, confession-of-judgment ban, debit limits
December 31, 2026
Texas — registration deadline for providers and brokers
The New York and California laws are the most detailed: both require an estimated APR, so you can compare a factor-rate offer with a bank loan on the same scale. Texas took a different approach. Its law requires prescribed disclosures on sales-based financing offers under $1 million, voids confessions of judgment in those contracts, restricts automatic debits, and requires providers and brokers to register with the Office of Consumer Credit Commissioner by December 31, 2026, with penalties of up to $10,000 per violation. It does not cap rates.
If you're outside these states, you can still ask any lender for the same information: the total repayment, every fee, the payment amount and schedule, and an APR. A lender that won't provide it is telling you something.
Renewals, stacking and other traps
Renewals that charge twice. Short-term lenders often offer to "renew" once you've repaid half the balance. With fixed-fee pricing, the new loan pays off the old balance, and if the remaining unpaid fee isn't forgiven, you pay the old fee on money you never got to use and a new fee on the whole renewed amount. Ask for the payoff figure and whether any unearned fee is rebated before you agree.
Stacking. Taking a second short-term loan or advance while the first is outstanding multiplies daily debits. Many contracts prohibit it and treat it as a default. If you're tempted to stack to cover payments, the business has a cash flow problem that more short-term debt won't solve.
Prepayment that saves nothing. On factor-rate products, paying early usually doesn't reduce the total unless the contract offers a discount. Get early-payoff terms in writing.
Personal guarantees and liens. Most short-term loans are marketed as unsecured but come with a personal guarantee and often a blanket UCC lien. Our unsecured business loans guide explains what those mean for you.
Broker fees. Brokers may be paid by the lender, by you, or both. Ask who pays the broker and how much, and check whether your state requires the broker to register.
How to qualify and apply
Online short-term lenders typically look for a minimum time in business, often six months to a year, a minimum monthly or annual revenue, and an acceptable owner credit history. They rely heavily on recent bank statements to judge average balances, deposit consistency and overdrafts. Banks ask for more: tax returns, financial statements and a debt schedule. Our business loan documents guide lists what each kind of lender requests.
Applying for a short-term loan the smart way
- 1
Size the need
Work out exactly how much you need and when the money will come back. Borrowing extra just because it's offered raises the fixed cost.
- 2
Get at least three offers
Include your own bank or credit union and an SBA lender if time allows, alongside online lenders.
- 3
Convert every offer to an APR and total cost
Use the disclosure form if your state requires one; otherwise ask for total repayment, fees and the payment schedule and calculate it yourself.
- 4
Check the payment schedule against your deposits
Make sure daily or weekly debits fit your actual cash pattern, including slow weeks.
- 5
Read the default, renewal and prepayment terms
Look for confessions of judgment, stacking bans, returned-payment fees and whether early payoff saves money.
Tip: Keep a copy of the signed contract and every disclosure.
Official links
- SBA — Types of 7(a) loans (CAPLines, Express)Short-term and revolving SBA options
- SBA — FY 2027 7(a) fee notice0.25% fee on loans of 12 months or less
- New York — Financial Services Law §803Required commercial financing disclosures
- California DFPI — Commercial financing disclosuresDisclosure rules and complaints
- Texas OCCC — Commercial sales-based financeRegistration of providers and brokers
- Federal Reserve — H.15 Selected Interest RatesCurrent prime rate
What to do next
Before taking a short-term loan, price the same need as a line of credit and, if you have a few weeks, as an SBA CAPLines or Express line. If you go ahead, borrow only what the opportunity requires, convert the offer to an APR, and make sure the payment schedule fits your deposits. Compare structures in our working capital loan guide and business line of credit guide.
This is general information, not legal, tax or financial advice — confirm on the official source or with a professional.
Frequently asked questions
There's no legal definition, but lenders generally use the term for loans repaid within about 18 months, most often 3 to 12 months. Payments are usually daily or weekly, debited automatically from your business bank account. SBA treats loans with a maturity of 12 months or less as a separate fee category, charging an upfront guaranty fee of just 0.25% of the guaranteed portion for fiscal year 2027.
Multiply the amount advanced by the factor rate to get the total repayment, then work out the annual rate that makes your scheduled payments equal the cash you actually received. A spreadsheet's RATE function does this: periodic rate times payments per year gives the APR. A 1.30 factor over six months with daily payments works out to roughly 109% APR, or about 123% if a 3% fee is deducted upfront.
They can be when the money produces a quick, predictable return, such as buying inventory you already have orders for, and you can absorb frequent payments. They're a poor fit for long-term purchases or for covering ongoing losses. Because the dollar cost is concentrated into a few months, the effective annual rate is usually much higher than on a bank loan or line of credit.
Only if the contract says so. With factor-rate products, the total payback is usually fixed when you sign, so paying early saves nothing unless the lender offers an early-payoff discount in writing. Interest-bearing loans normally save interest when prepaid, though some charge a prepayment fee. Ask for the payoff terms before signing; New York and California disclosure forms show them.
A short-term loan gives you a lump sum that you repay on a fixed schedule, whether or not you still need the cash. A line of credit lets you draw only what you need, pay interest only on the outstanding balance and borrow again as you repay. For uneven or seasonal needs, a line usually costs less; a short-term loan can be easier to get quickly.
There's no federal rate cap on business loans, but a growing number of states require cost disclosures. New York covers offers up to $2.5 million and California offers of $500,000 or less, both with an estimated APR. Texas requires disclosures on sales-based financing under $1 million and registration by December 31, 2026. Several other states have similar laws.
Sources & verification
Figures on this page were checked against the sources below when it was last reviewed on 12 October 2026. Each rate and limit is stored once with its own official source and review date, and official update channels are monitored daily so changes are picked up. How we verify
- 1.2026 Report on Employer Firms: Findings from the 2025 Small Business Credit Survey — Federal Reserve Banks · accessed 12 October 2026
- 2.Types of 7(a) loans — U.S. Small Business Administration · accessed 12 October 2026
- 3.Information Notice 5000-881797 — FY 2027 7(a) program fees — U.S. Small Business Administration · accessed 12 October 2026
- 4.H.15 Selected Interest Rates — Board of Governors of the Federal Reserve System · accessed 12 October 2026
- 5.New York Financial Services Law §803 — Sales-based financing and other disclosures — New York State Senate · accessed 12 October 2026
- 6.New York Financial Services Law §802 — Exemptions — New York State Senate · accessed 12 October 2026
- 7.Commercial Financing Disclosures — California Department of Financial Protection and Innovation · accessed 12 October 2026
- 8.Texas H.B. No. 700 (enrolled) — Commercial sales-based financing, Finance Code Chapter 398 — Texas Legislature · accessed 12 October 2026
- 9.Cash Advance Firm to Pay $9.8M to Settle FTC Complaint It Overcharged Small Businesses — Federal Trade Commission · accessed 12 October 2026
- 10.Small Business Lending Survey — Q2 2026 — Federal Reserve Bank of Kansas City · accessed 12 October 2026
- 11.State Commercial Financing Disclosure Laws: Recent Developments and Compliance Considerations — Venable LLP · accessed 12 October 2026
MSMETOOLS is an independent platform and is not affiliated with any government agency, ministry or department.
Tools for this
Working Capital Calculator
Check working capital, current and quick ratios.
EMI Calculator
Calculate loan EMIs for business and personal loans.
Loan Eligibility Calculator
Check your business loan eligibility based on income and existing loans.
Related guides
 Working Capital Loan 2026: Types, SBA Options & CostsRead guide
 Unsecured Business Loans 2026: Rates, Liens & How to QualifyRead guide
 Invoice Factoring (2026): Rates, Recourse & True APRRead guide
 SBA Express Loan 2026: Limits, Rates, Fees & TurnaroundRead guide
Official links open the government site in a new tab.