 HR, payroll & employment
Expenses and Benefits for Employers in 2026: What's Tax-Free, What's Taxable and How to Report It
Expenses and benefits for employers in 2026: what's exempt, £50 trivial benefits, the £150 party rule, 2026 reimbursement changes, P11D vs payroll, Class 1A.
 Edited by Sumeet YadavFounder & editor, MSMETOOLS · fact-checked against official sources
Contents (10)
- 1. Expenses vs benefits: the distinction that drives everything
- 2. Business expenses you can pay tax-free
- 3. The April 2026 changes: reimbursements and homeworking
- 4. Benefits that are exempt
- 5. Taxable benefits and Class 1A
- 6. PAYE Settlement Agreements
- 7. Worked example: a small firm's year
- 8. Reporting from 2027: payroll replaces the P11D
- 9. Common mistakes
- 10. What to do next
Every employer that pays for anything beyond wages, from a train ticket to a Christmas party to private medical cover, has to decide how it's taxed. Get it right and much of it is tax-free with no paperwork. Get it wrong and you face a bill for the employees' tax plus employer National Insurance, interest and penalties. This guide is for small business owners, payroll managers and bookkeepers in 2026. It sorts expenses and benefits into what's exempt, what's taxable, and how each taxable item is reported, with the April 2026 changes and a worked year for a small firm. For the P11D form itself, see our P11D guide.
Quick answer
Business expenses an employee could have claimed tax relief on (travel, subsistence, tools) are exempt and not reported. So are a long list of specific benefits, including trivial benefits up to £50 and annual parties up to £150 a head. Other benefits are taxable: you report them on a P11D or payroll them, and pay Class 1A National Insurance at 15% by 22 July (19 July by cheque).
P11Ds and the P11D(b) for 2026-27 are due by 6 July 2027, filed online
From 6 April 2026, reimbursed eye tests, flu jabs and homeworking equipment are tax-free
Cash, cash vouchers and paying an employee's personal bills go through payroll with Class 1 NI
Mileage is tax-free up to 55p a mile for the first 10,000 business miles
Cars, vans, fuel and medical benefits must be payrolled from 6 April 2027
Expenses vs benefits: the distinction that drives everything
HMRC treats two different things under one heading. Expenses are costs the employee incurs, or you pay, in doing their job: a hotel on a client visit, a train fare, professional subscriptions. Benefits are things the employee gets for personal use or enjoyment because of their job: a company car they also drive at weekends, health insurance, a gym membership.
The test for expenses is whether the employee would have been entitled to a tax deduction if they had paid it themselves. If they would, you can pay or reimburse it with no tax, no National Insurance and no reporting. That's the exemption for paid or reimbursed expenses, which replaced the old system of dispensations on 6 April 2016. If they wouldn't, the payment is earnings, however it's labelled.
Benefits are taxable by default unless a specific exemption applies. The employee pays income tax on the benefit's cash equivalent, usually through a reduced tax code or through payroll, and the employer pays Class 1A National Insurance on it. Employees don't pay National Insurance on benefits in kind, which is one reason benefits remain popular.
There's a third category that people miss: items that look like benefits but are treated as pay. If you give an employee cash, a voucher that can be exchanged for cash, or settle a bill that's in their own name, such as their home phone contract or their child's school fees, that's earnings. Tax goes through PAYE and both sides pay Class 1 National Insurance as if it were salary.
How to treat a payment to or for an employee
Step 1
Is it a business expense they could deduct?
Step 2
Yes: exempt, no report
travel, subsistence, tools
Step 3
No: is there a specific exemption?
Step 4
Yes: exempt
trivial, party, phone…
Step 5
No: cash or their own bill?
Step 6
Payroll with Class 1 NI
Step 7
Otherwise P11D or payroll + Class 1A
15%
Business expenses you can pay tax-free
Under the exemption for paid or reimbursed expenses, you don't need to report or tax business costs the employee could have claimed. The common ones:
- Business travel, meaning journeys in the course of the job and to temporary workplaces, but not ordinary commuting to a permanent workplace. That includes fares, hotels and reasonable subsistence on the trip.
- Business entertainment of clients, where the employee is reimbursed for a genuine business cost.
- Professional fees and subscriptions to bodies on HMRC's approved list, where membership is relevant to the job.
- Tools, uniforms and protective clothing needed for the work.
- Business calls on a personal phone, if you can identify them from the bill.
For subsistence, you can pay HMRC's benchmark scale rates, or rates you've agreed with HMRC, without checking receipts, as long as you confirm the employee actually made the qualifying journey. Bespoke rates need an approval notice from HMRC, which lasts up to five years.
The exemption doesn't cover everything. HMRC's guidance excludes payments made under salary sacrifice, round-sum allowances (a flat £100 a month "for expenses" without checking what's spent) and mileage, which has its own rules. A round-sum allowance is earnings: put it through payroll with tax and Class 1 National Insurance.
Mileage
For employees using their own vehicle on business, you can pay approved mileage allowance payments tax-free. From 6 April 2026 the car and van rate rose to 55p a mile for the first 10,000 business miles in the tax year, from 45p a mile, and stays at 25p a mile above that. Motorcycles are 24p a mile and bicycles 20p a mile.
Tax and National Insurance work slightly differently. For tax, the 10,000-mile split applies, and any excess goes on the P11D or through payroll. For National Insurance, GOV.UK says to multiply all business miles in the earnings period by the higher rate; there's no 10,000-mile split, and any excess is added to pay for Class 1 National Insurance through payroll. Our mileage allowance guide covers passengers and fuel rates for company cars.
The April 2026 changes: reimbursements and homeworking
Until April 2026, a quirk in the law meant some exemptions only worked if the employer paid the supplier or gave a voucher. If an employee paid for their own eye test and the employer reimbursed them, it was taxable. HMRC's April 2026 Employer Bulletin confirms that from 6 April 2026 the following can be reimbursed without income tax or Class 1 National Insurance:
- eye tests for display screen equipment users, and glasses needed for screen work;
- seasonal flu vaccinations;
- certain equipment needed to do the job, including equipment to work effectively from home.
The exemption applies automatically when the legal conditions are met: no claim, approval or change to reporting is needed. Costs reimbursed before 6 April 2026 follow the old rules. HMRC's manual adds that the flu vaccine exemption doesn't apply where it's provided through salary sacrifice or for family members.
The same date brought a change in the other direction. Employees can no longer claim tax relief from HMRC for extra household costs of working from home when the employer doesn't pay them. Employers can still pay up to £6 a week (£26 a month for monthly-paid staff) tax-free to employees who regularly work from home under an agreed arrangement, or more if the employee can show actual extra costs. That shifts the decision onto employers: if you want home workers to get relief, you now have to pay it. Our working from home expenses guide has the employee side.
Benefits that are exempt
A long list of benefits carries no tax or National Insurance and no reporting. The ones small employers use most:
Common exempt benefits (2026-27)
| Benefit | Limit or condition |
|---|---|
Trivial benefits | Up to £50 each; not cash, not a reward, not contractual; £300 a year cap for close-company directors |
Annual party or event | Up to £150 a head a year in total, open to all staff (or all at a location) |
Mobile phone | One per employee, including private use |
Homeworking costs | £6 a week without evidence (£26 a month monthly) |
Relocation | Up to £8,000 of qualifying costs |
Pension contributions | Employer contributions to a registered scheme |
Pensions advice | Up to £500 a year |
Cycle-to-work | Bikes and safety equipment mainly for commuting |
Eye tests and flu jabs | Provided, vouchered or reimbursed from 6 April 2026 |
Workplace parking, canteen open to all, work-related training | No limit |
Trivial benefits
- Limit or condition
Up to £50 each; not cash, not a reward, not contractual; £300 a year cap for close-company directors
Annual party or event
- Limit or condition
Up to £150 a head a year in total, open to all staff (or all at a location)
Mobile phone
- Limit or condition
One per employee, including private use
Homeworking costs
- Limit or condition
£6 a week without evidence (£26 a month monthly)
Relocation
- Limit or condition
Up to £8,000 of qualifying costs
Pension contributions
- Limit or condition
Employer contributions to a registered scheme
Pensions advice
- Limit or condition
Up to £500 a year
Cycle-to-work
- Limit or condition
Bikes and safety equipment mainly for commuting
Eye tests and flu jabs
- Limit or condition
Provided, vouchered or reimbursed from 6 April 2026
Workplace parking, canteen open to all, work-related training
- Limit or condition
No limit
Trivial benefits
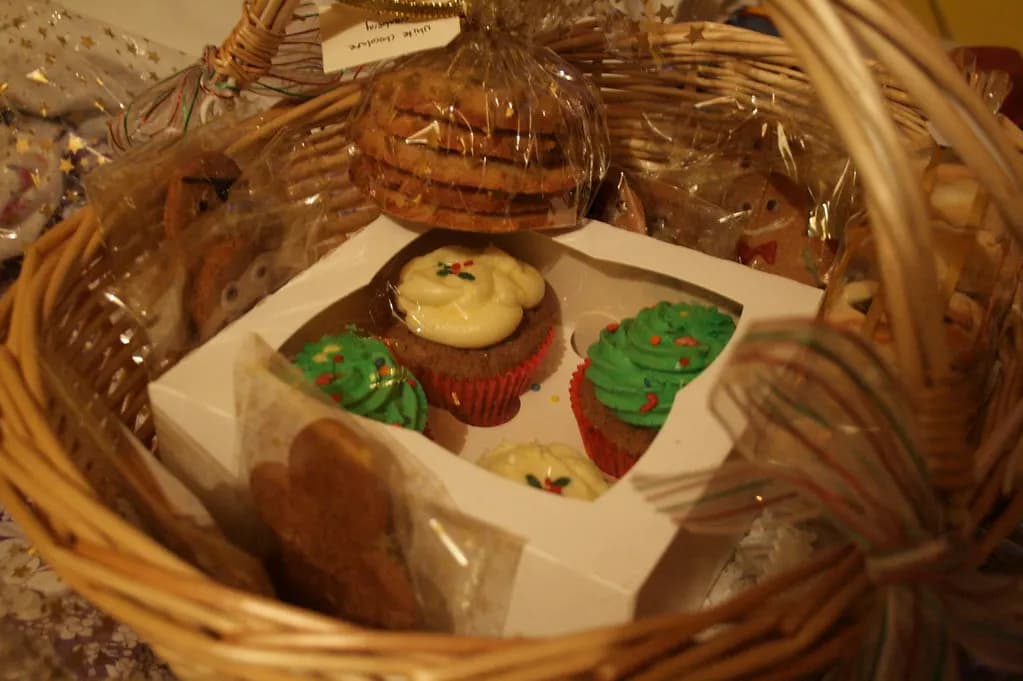
The trivial benefits rule covers the small gestures that make up most staff perks: birthday flowers, a bottle of wine at Christmas, a takeaway after a late shift. GOV.UK sets four conditions: the benefit cost £50 or less to provide; it isn't cash or a cash voucher; it isn't a reward for work or performance; and it isn't in the employee's contract. A non-cash gift card that can only be spent in shops counts as a voucher you can give, as long as it's within the limit.
The limit is a cliff edge, not an allowance. A £55 gift is taxable in full, not just the £5 over. For team gifts, the test is the cost per person, so a £300 team lunch for eight is £37.50 each and can qualify. There's no annual limit for ordinary employees, but directors of a close company, broadly one controlled by five or fewer shareholders, can receive no more than £300 of trivial benefits in a tax year.
Staff parties
The annual function exemption lets you hold a party or similar event tax-free if it's open to all employees, or all employees at one location, and the total cost per head for the year's events is no more than £150 a head. Cost per head includes VAT, transport and accommodation, and is calculated by dividing the total by everyone attending, including guests.
It's another cliff edge. If one event costs £160 a head, the whole £160 is taxable. If you hold two events that together exceed £150 a head, you can apply the exemption to whichever combination fits, and the rest is taxable. Most employers settle the tax on a taxable party through a PAYE Settlement Agreement rather than reporting it for every guest.
Taxable benefits and Class 1A
Anything not covered by an exemption is taxable. The big ones are company cars and fuel, vans, private medical insurance, gym memberships, beneficial loans over the small loans limit, accommodation, and non-business use of company assets. Each has its own valuation rule, usually the cost to the employer, or a statutory formula for cars, vans and loans. The company car tax guide covers the car percentages.
For every taxable benefit, the employer has two obligations. First, make sure the employee is taxed, either by reporting it on a P11D after the year end (HMRC then adjusts their tax code) or by payrolling it in-year. Second, pay Class 1A National Insurance at 15% on the taxable value. Class 1A is declared on the P11D(b) by 6 July and paid by 22 July (19 July by cheque) after the tax year. HMRC's April 2026 bulletin reminds employers that P11Ds and the P11D(b) must be filed online, together. Late P11D(b)s attract penalties of £100 per 50 employees for each month or part month.
Where the benefit is provided through salary sacrifice or a flexible benefits choice, the optional remuneration rules usually tax the higher of the salary given up and the benefit value. Pensions, cycle-to-work and cars at 75g/km or less are among the exceptions. See our salary sacrifice guide.
PAYE Settlement Agreements
Some benefits are too small, irregular or awkward to tax on each employee: a one-off taxable event, a gift from a client passed on to staff, or a taxable party where you'd rather staff weren't taxed. A PAYE Settlement Agreement lets the employer pay the tax for them, grossed up, along with Class 1B National Insurance, in a single annual payment.
Items in a PSA don't go on P11Ds, through payroll or into the Class 1A calculation. You must apply by 5 July after the tax year it first covers, tell HMRC the value of the items, and pay by 22 October after the tax year (19 October by post). Because the employer pays the employees' tax as well as its own National Insurance, a PSA costs more per pound of benefit than Class 1A on a P11D, but it keeps the perk genuinely free for the employee.
Worked example: a small firm's year
Northfield Plumbing Ltd has eight employees in 2026-27. Here's how its spending sorts out.
| Item | Cost | Treatment | Employer cost beyond the item |
|---|---|---|---|
| Christmas party, £118 a head incl. VAT, all staff | £944 | Exempt annual function | £0 |
| Summer barbecue, £45 a head | £360 | Taxable: with the party it exceeds £150 a head; settled by PSA | PSA tax and Class 1B |
| £40 hampers for every employee | £320 | Trivial benefit | £0 |
| Private medical cover for two supervisors | £2,200 | Taxable benefit on P11D | £330 Class 1A |
| Engineer's mileage, 12,000 miles at 60p | £7,200 | Tax-free to £6,000; NI-free to £6,600 | £90 Class 1 NI on £600, £1,200 taxed for the employee |
| Train fares and hotels for a training course | £640 | Exempt business travel and training | £0 |
| £30 a month to a phone sales manager "for expenses" | £360 | Round-sum allowance: earnings | Class 1 NI through payroll |
The party and barbecue together cost £163 a head, so only one can be exempt. The firm exempts the larger party and settles the £45 barbecue through a PSA. The mileage is the subtle one: for tax, 10,000 miles at 55p a mile plus 2,000 at 25p a mile gives an approved amount of £6,000, so £1,200 is taxable and goes on the P11D or through payroll. For National Insurance, all 12,000 miles at 55p gives £6,600, so only £600 attracts Class 1 National Insurance through payroll, costing the employer £90 at 15%.
The P11Ds for the two supervisors, and the engineer's mileage excess, go to HMRC by 6 July 2027 with a P11D(b) showing £330 of Class 1A, payable by 22 July 2027.
Reporting from 2027: payroll replaces the P11D
The way benefits are reported is changing. Voluntary payrolling closed to new registrations on 6 April 2026, ahead of mandatory payrolling. From 6 April 2027, company cars, car fuel, vans, van fuel and employer-provided medical benefits must be reported and taxed through payroll in real time, with Class 1A reported through payroll too. Most other benefits follow from 6 April 2028, while loans and accommodation stay voluntary. For Northfield, that means the supervisors' medical cover moves into monthly payroll from April 2027. Our payrolling benefits guide explains what to prepare.
Setting up an expenses and benefits policy
- 1
List everything you pay for
Go through the bank and card statements: travel, gifts, subscriptions, insurance, parties, phones, allowances.
- 2
Sort each item
Deductible expense, specific exemption, cash-equivalent pay, or taxable benefit.
- 3
Write the rules down
A short policy covering travel, subsistence rates, receipts, mileage rates and gifts stops ad hoc payments that turn into earnings.
Tip: Pay mileage at the approved rate. Paying above it creates reporting work for small amounts.
- 4
Choose how to settle the awkward items
Agree a PSA by 5 July after the tax year for one-off or minor taxable items.
- 5
Prepare for payroll reporting
Collect car, van and medical benefit data and confirm your payroll software is ready for 6 April 2027.
Common mistakes
- Treating a round-sum allowance as an expense. Without checking what's spent, it's pay. Run it through payroll.
- Missing the cliff edges. A £52 gift or a £151-a-head party is fully taxable.
- Paying a personal bill as a "benefit". Paying the employee's own phone or utility contract is earnings with Class 1 National Insurance, not a P11D item.
- Forgetting Class 1A on payrolled benefits. Payrolling handles the employee's tax, but for 2026-27 the employer still files a P11D(b) and pays Class 1A by 22 July (19 July by cheque).
- Ignoring the director cap. Close-company directors can receive only £300 of trivial benefits a year; the cap is designed to stop repeated small gifts being used as tax-free pay.
- Reimbursing eye tests or flu jabs before April 2026 and treating them as exempt. Earlier reimbursements follow the old rules and are generally taxable.
When you find a mistake, correct it: amend P11Ds online, pay additional Class 1A, and for underpaid PAYE consider a PSA or a voluntary disclosure. HMRC charges interest on late Class 1A and can charge penalties for careless errors, reduced if you tell it first.
Official links
- Expenses and benefits for employersOverview and A to Z
- Exemption for paid or reimbursed expenses480 Chapter 2
- Trivial benefits£50 rule and director cap
- Homeworking expenses£6 a week
- Mileage: rules for National InsuranceApproved rates
- PAYE Settlement AgreementsApply and pay
- Employer Bulletin April 20262026 reimbursement changes
What to do next
Pull last year's expenses ledger and sort each line into exempt, payroll or P11D, using the flow at the top of this page. Write a one-page expenses policy, set mileage at the approved rate, and decide now whether a PSA would tidy up your party and gift costs before the 5 July after the tax year deadline. Then read the payrolling benefits guide to get ready for April 2027, and use the salary slip generator to check how payrolled items will look to staff.
This is general information, not legal or tax advice — confirm on the official source or with a professional.
Frequently asked questions
The main tax-free items are business expenses the employee could have claimed themselves (travel, subsistence, tools), mileage up to the approved rates, trivial benefits up to £50, annual parties up to £150 a head, one mobile phone, employer pension contributions, cycle-to-work, workplace parking, eye tests for screen users, flu jabs, relocation up to £8,000 and £6 a week for homeworking costs.
A benefit is exempt if it cost £50 or less to provide, isn't cash or a cash voucher, isn't a reward for work or performance, and isn't in the employee's contract. There's no annual limit for ordinary employees, but directors of close companies are capped at £300 of trivial benefits a tax year. If the cost is £51, the whole amount is taxable, not just the £1 above the limit.
Yes, on most taxable benefits. Employers pay Class 1A National Insurance at 15% on the taxable value of benefits reported on P11Ds or payrolled, paid by 22 July after the tax year. Employees don't pay National Insurance on benefits in kind. Cash-like items, such as paying an employee's personal bill or giving cash vouchers, attract Class 1 National Insurance through payroll instead.
Not if they're covered by the exemption for paid or reimbursed expenses. If the employee would have been entitled to a tax deduction for the cost, such as business travel or subsistence on a business trip, you don't report it or deduct tax. Expenses that aren't deductible, such as ordinary commuting or round-sum allowances, are taxable and must be reported or put through payroll.
From 6 April 2026, employers can reimburse eye tests and glasses for screen users, seasonal flu vaccinations and equipment for working from home without tax or National Insurance, matching the treatment when the employer pays the provider directly. At the same time, employees lost the right to claim tax relief from HMRC for non-reimbursed homeworking costs, though employers can still pay £6 a week tax-free.
A PSA lets an employer pay the employees' tax and National Insurance on minor, irregular or impracticable items, such as a one-off taxable staff event or small gifts to staff, in one annual payment. The items don't go on P11Ds or through payroll. You apply by 5 July after the tax year and pay by 22 October, or 19 October by post.
Sources & verification
Figures on this page were checked against the sources below when it was last reviewed on 13 October 2026. Each rate and limit is stored once with its own official source and review date, and official update channels are monitored daily so changes are picked up. How we verify
- 1.Expenses and benefits for employers — GOV.UK · accessed 13 October 2026
- 2.Exemption for paid or reimbursed expenses (480: Chapter 2) — HMRC · accessed 13 October 2026
- 3.April 2026 issue of the Employer Bulletin — HMRC · accessed 13 October 2026
- 4.Expenses and benefits: trivial benefits — GOV.UK · accessed 13 October 2026
- 5.Homeworking expenses and benefits that are exempt from tax — GOV.UK · accessed 13 October 2026
- 6.Business travel mileage: rules for tax and rules for National Insurance — GOV.UK · accessed 13 October 2026
- 7.Relocation expenses: what's exempt — GOV.UK · accessed 13 October 2026
- 8.PAYE Settlement Agreements: deadlines and payment — GOV.UK · accessed 13 October 2026
- 9.Expanding workplace benefits relief — HMRC · accessed 13 October 2026
- 10.Institute welcomes extension of employee benefit tax breaks — Chartered Institute of Taxation · accessed 13 October 2026
MSMETOOLS is an independent platform and is not affiliated with any government agency, ministry or department.
Tools for this
Salary Slip Generator
Create professional salary slips in seconds.
Budget Planner
Plan and track your business budget easily.
Related guides
 P11D 2026: Deadlines, Class 1A & Benefits in Kind GuideRead guide
 Payrolling Benefits in Kind 2026: 2027 Mandatory RulesRead guide
 Termination Payments Tax 2026: £30,000 Rule, PENP & Class 1ARead guide
 Salary Sacrifice 2026: Pensions, NI Savings & the 2029 CapRead guide
Official links open the government site in a new tab.