 Income tax
Fringe Benefits Tax (FBT) in Australia (2026): Rates, Cars, EVs and Exemptions
Fringe benefits tax in Australia for 2026: the 47% rate, the April–March FBT year, car benefits, EV exemption and 2027 changes, minor benefits and A$ examples.
 Edited by Sumeet YadavFounder & editor, MSMETOOLS · fact-checked against official sources
Contents (9)
- 1. What fringe benefits tax is and who pays it
- 2. The FBT year, registration and lodgment
- 3. How FBT is calculated
- 4. Car fringe benefits: statutory formula vs operating cost
- 5. Worked example: a car under both methods
- 6. The electric car exemption in 2026
- 7. Exemptions small businesses use most
- 8. Common FBT mistakes and how they get fixed
- 9. What to do next
Fringe benefits tax catches small employers off guard because it runs on its own calendar, charges the employer rather than the employee, and is calculated on a grossed-up figure that makes a modest perk expensive. This guide is for Australian business owners who give staff — or themselves as company directors — a car, a car park, a gym membership, a paid bill or a salary-packaged EV. It covers the 2026 rate and FBT year, which benefits are taxable, how car benefits are valued, the electric car exemption and the changes announced for 2027, the exemptions that matter most to small businesses, and worked examples in Australian dollars.
Quick answer
Fringe benefits tax (FBT) is a tax employers pay on non-cash benefits given to employees or their associates. The rate is 47%, applied to the benefit's grossed-up taxable value, for the FBT year 1 April 2026 – 31 March 2027. Eligible electric cars remain exempt until at least 31 March 2027; plug-in hybrids lost the exemption for new arrangements from 1 April 2025.
Gross-up rates: 2.0802 (you can claim GST credits) or 1.8868 (you can't)
Car benefits: 20% statutory formula or the operating cost method with a logbook
Minor benefits under A$300 given infrequently are usually exempt
Return and payment due 21 May (25 June through a tax agent)
Proposed: full EV exemption capped at A$75,000 from 1 April 2027 — not yet law
What fringe benefits tax is and who pays it
A fringe benefit is a "payment" to an employee in a form other than salary or wages. The employer pays FBT on it, separately from income tax, and the employee doesn't pay income tax on that benefit. The tax exists so that paying people in perks isn't cheaper than paying them in cash. That is why the rate, 47%, equals the top personal tax rate plus the 2% Medicare levy.
FBT applies when you provide a benefit to an employee (current, future or past), to an employee's associate such as a spouse or child, or through a third party under an arrangement with you. "Employee" includes company directors who receive benefits from the company — which is the trap for many small company owners. A sole trader or partner taking a benefit for themselves isn't an employee, so no FBT arises; the private portion simply isn't deductible.
Common fringe benefits for small businesses include a work car available for private use, car parking near the workplace, paying an employee's private expense (a phone bill, school fees, gym membership), low-interest loans, entertainment such as meals or event tickets, and goods sold to staff at a discount. Salary packaging — where an employee gives up pay in exchange for a benefit — creates fringe benefits too.
Not everything is a fringe benefit. Salary and wages, super contributions to a complying fund, employee share scheme interests, and termination payments are outside FBT. Many items are also specifically exempt, as covered below.
FBT at a glance — FBT year ending 31 March 2027
47%
FBT rate
Unchanged since 2023
2.0802
Type 1 gross-up
GST credit claimable
1.8868
Type 2 gross-up
No GST credit
A$11.48 a day
Car parking threshold
8.27%
Benchmark interest rate
Loans and operating cost method
The FBT year, registration and lodgment
The FBT year runs from 1 April to 31 March. The year that matters now began on 1 April 2026 and ends on 31 March 2027, and the ATO labels it the "2027 FBT year". This mismatch with the 1 July income year is the most common reason small businesses miss FBT: benefits provided in, say, April belong to an FBT year that has nothing to do with the income tax return you're preparing at the time.
If you provide fringe benefits that create a liability, you need to register for FBT — this can be done through the Business Registration Service when you set up, or later through the ATO. You then lodge an annual FBT return and pay by 21 May. If a registered tax agent lodges electronically for you, the date is generally 25 June, provided you were on the agent's FBT client list by 21 May. If you owed A$3,000 or more of FBT in the previous year, the ATO will have you pay quarterly instalments through your BAS, which are credited against the annual return.
Once registered, you lodge a return every year unless you tell the ATO you won't have a liability (a non-lodgment advice). Late lodgment attracts failure-to-lodge penalties, and unpaid FBT accrues the general interest charge.
FBT is deductible
The cost of providing a fringe benefit and the FBT you pay are generally both deductible for income tax. GST credits are claimable on many benefits. This is why the gross-up rates exist: they put the benefit on the same footing as the pre-tax salary the employee would otherwise need to earn to buy it.
How FBT is calculated
Every FBT calculation follows the same three steps. First, work out the taxable value of each benefit using the valuation rule for that type of benefit, minus any after-tax contribution the employee pays you. Second, gross it up: multiply type 1 benefits (where you can claim a GST credit) by 2.0802 and type 2 benefits (where you can't, such as many exempt or input-taxed items) by 1.8868. Third, multiply the total by 47%.
From benefit to FBT payable
Step 1
Identify benefit
Step 2
Taxable value
valuation rule − employee contribution
Step 3
Gross up
× 2.0802 or × 1.8868
Step 4
× 47%
FBT payable
The otherwise deductible rule can reduce the taxable value. If the employee could have claimed an income tax deduction for the expense had they paid it themselves — say, a work-related training course — the taxable value is reduced by that deductible amount, often to nil. For some benefits you need a declaration from the employee to use it.
Employee contributions are the other big lever. An employee who pays you after-tax money towards a benefit reduces its taxable value dollar for dollar. Many salary-packaged car arrangements use contributions to bring the taxable value of a car to zero, so the employer pays no FBT. Contributions you receive are assessable income to you, and GST may apply.
Car fringe benefits: statutory formula vs operating cost
A car fringe benefit arises when a car you own or lease is used privately by an employee, or is available for their private use — a car garaged at an employee's home is treated as available, even if it isn't driven. Commuting between home and work counts as private use. You can value a car benefit two ways and choose whichever gives the lower result, as long as you have the records the operating cost method needs.
The two ways to value a car fringe benefit
| Statutory formula method | Operating cost method | |
|---|---|---|
Starting point | Car's base value (cost incl. GST and dealer delivery, excl. rego and stamp duty) | Total operating costs, plus deemed depreciation and deemed interest if you own the car |
Rate applied | 20% flat, whatever the kilometres | Private-use percentage from a logbook |
Records | Base value and days available | 12-week logbook, odometer readings and all costs |
Best for | Cars with high private use, or no logbook | Cars with high business use |
Deemed figures | Base value falls by one-third after 4 full FBT years held | Depreciation 25% diminishing value; interest at 8.27% |
Starting point
- Statutory formula method
Car's base value (cost incl. GST and dealer delivery, excl. rego and stamp duty)
- Operating cost method
Total operating costs, plus deemed depreciation and deemed interest if you own the car
Rate applied
- Statutory formula method
20% flat, whatever the kilometres
- Operating cost method
Private-use percentage from a logbook
Records
- Statutory formula method
Base value and days available
- Operating cost method
12-week logbook, odometer readings and all costs
Best for
- Statutory formula method
Cars with high private use, or no logbook
- Operating cost method
Cars with high business use
Deemed figures
- Statutory formula method
Base value falls by one-third after 4 full FBT years held
- Operating cost method
Depreciation 25% diminishing value; interest at 8.27%
Under the statutory formula, the taxable value is the base value × 20% × the days the car was available for private use ÷ days in the year, minus employee contributions. Days the car is in for repairs or sitting at the business while the employee is away can be excluded. The method ignores kilometres completely, so a car driven 95% for work is valued the same as a weekend car.
Under the operating cost method, you add up all the car's costs for the FBT year — fuel, repairs, rego, insurance, lease payments, or if you own it, deemed depreciation at 25% diminishing value and deemed interest at the benchmark rate — and multiply by the private-use percentage from a valid logbook. If you don't have a logbook, the private use is treated as 100%, which usually makes this method worse than the statutory formula.
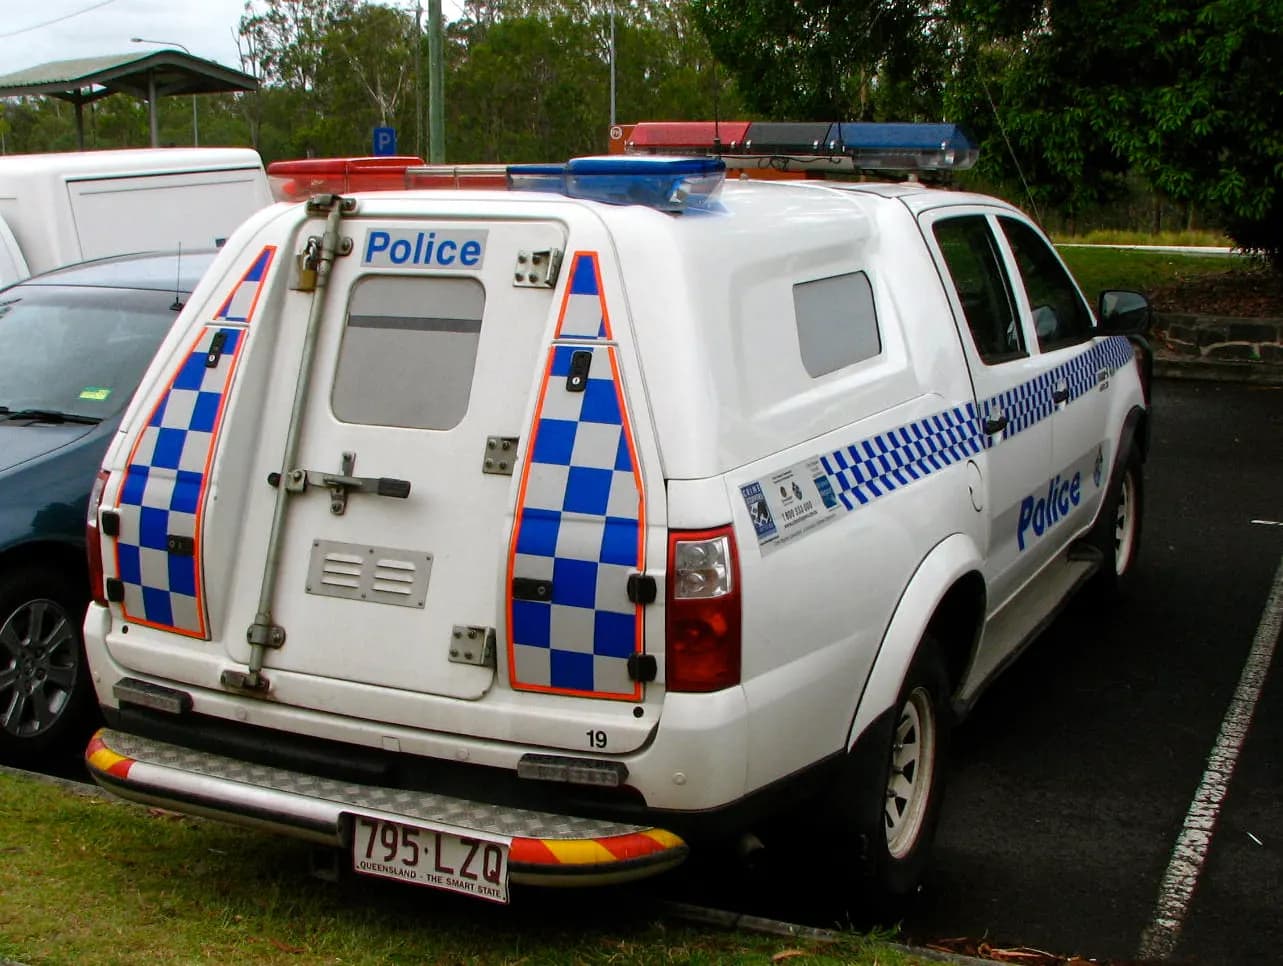
Utes, vans and work vehicles
Vehicles designed to carry a load of a tonne or more, or nine or more passengers, aren't "cars" for FBT, and panel vans and single-cab utes designed to carry less than a tonne get a specific exemption. For both, private use is exempt if it is limited to travel between home and work, travel incidental to work, and minor, infrequent and irregular private trips. A tradie who takes the work ute home each night and occasionally drops into the hardware store on a Saturday is usually fine; one who tows the family caravan on holiday isn't. Dual-cab utes designed to carry less than a tonne need more care, because the ATO treats many of them as passenger cars — check its ute guidance before assuming the exemption.
Worked example: a car under both methods
Ravi runs a Brisbane IT support company, Ravi Tech Pty Ltd, which is registered for GST. It buys a petrol sedan with a base value of A$45,000 and gives it to its service manager, Lena, for work and private use for the whole 2027 FBT year. Lena makes no contribution.
Under the statutory formula the taxable value is A$45,000 × 20% = A$9,000. Because the company claimed GST credits on the car, it is a type 1 benefit, so the grossed-up value is A$9,000 × 2.0802 = A$18,721.80. FBT payable is A$18,721.80 × 47% = A$8,799.25.
Now suppose Lena kept a valid 12-week logbook showing 70% business use, and the car's total costs for the year — fuel, rego, insurance, servicing, deemed depreciation and deemed interest — come to A$14,000. Under the operating cost method, the taxable value is the 30% private share, A$4,200. Grossed up: A$4,200 × 2.0802 = A$8,736.84. FBT: A$4,106.31 — less than half the statutory result.
If instead Lena contributed A$3,000 after tax towards the car under the statutory formula, the taxable value would drop to A$6,000 and the FBT to A$5,866.16. A contribution of A$9,000 would wipe out the FBT entirely, which is how many novated-lease packages are structured.
Plan the after-tax cost of a packaged car
The electric car exemption in 2026
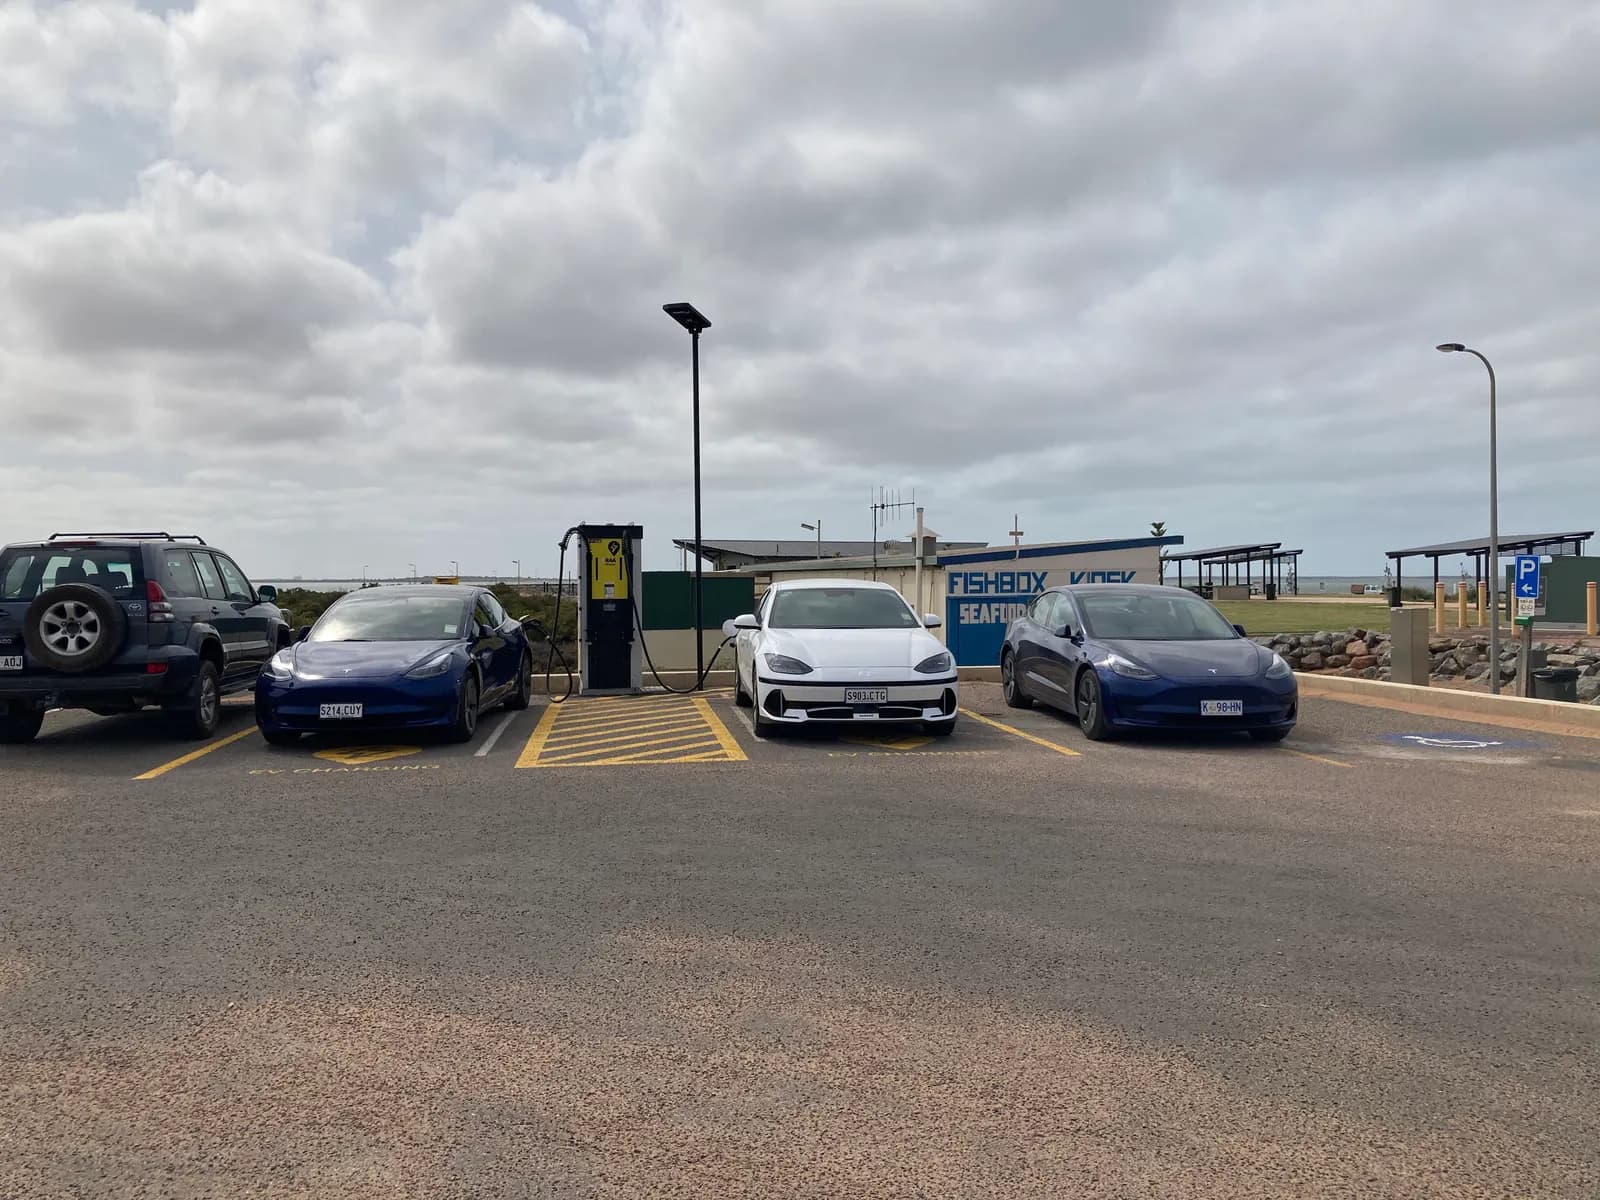
Since 1 July 2022, employers haven't paid FBT on the private use of an eligible electric car. That exemption continues for the FBT year ending 31 March 2027. A car qualifies when all these conditions are met: it is a battery electric or hydrogen fuel cell car designed to carry less than a tonne and fewer than nine passengers; it was first held and used on or after 1 July 2022; it is used by a current employee or their associate; and luxury car tax has never been payable on its importation or sale — in practice, its value was below the LCT threshold for fuel-efficient vehicles, which is A$91,661 for 2026-27 (up from A$91,387 in 2025-26).
Running costs that come with the car — registration, insurance, repairs and the electricity to charge it — are exempt too. A home charging station isn't; it may be a separate property or expense payment benefit. To value home-charged electricity for reporting or for vehicles that don't qualify, the ATO's practical compliance guideline lets you use a home charging rate of 5.47 cents per km for the FBT year starting 1 April 2026 (it was 4.20 cents for earlier years).
Exempt, but still reportable
An exempt EV is still a reportable fringe benefit. You work out its notional taxable value as if FBT applied and, if the employee's total reportable benefits exceed A$2,000, report the grossed-up amount (using the lower 1.8868 rate) through Single Touch Payroll. That amount doesn't change the employee's income tax, but it counts for income tests such as the Medicare levy surcharge, child support and some government payments.
For example, an EV with a base value of A$68,000 provided for the whole year has a notional taxable value of A$68,000 × 20% = A$13,600. The reportable amount is A$13,600 × 1.8868 = A$25,660.48 — no FBT, but that figure appears on the employee's income statement.
Plug-in hybrids lost the exemption from 1 April 2025
From 1 April 2025, plug-in hybrids are no longer zero or low emissions vehicles for FBT. Employers providing a new PHEV now pay FBT on it like any petrol car. A PHEV already exempt before that date keeps the exemption only while the employer has a financially binding commitment, entered into before 1 April 2025, to continue providing it for private use. Refinancing or extending a lease can end that protection.
What's proposed from 1 April 2027
On 5 May 2026, after Treasury's statutory review of the electric car discount, the Treasurer announced a three-stage wind-back. The existing exemption continues in full until 31 March 2027. From 1 April 2027 to 1 April 2029, the full exemption would apply only to EVs costing A$75,000 or less; dearer EVs below the fuel-efficient LCT threshold would get a 25% discount on FBT. From 1 April 2029, all eligible EVs below the threshold would get the 25% discount rather than a full exemption. Existing leases won't be affected.
Treasury released exposure draft legislation in September 2026, with consultation closing on 28 September 2026. In the draft, the 25% discount works through a reduced statutory formula rate of 15% instead of 20%, and the transition depends on when the last financially binding commitment for the car was made. As at October 2026 this is not yet law. If you are ordering an EV that will be delivered or packaged near 1 April 2027, get the commitment documented before that date and check whether the bill has passed.
Exemptions small businesses use most
FBT has dozens of exemptions and concessions. These are the ones that come up most for small employers.
Common exempt or concessional benefits
0/8The minor benefits exemption
Section 58P of the Fringe Benefits Tax Assessment Act exempts a benefit whose notional taxable value is less than A$300 where it would be unreasonable to treat it as a fringe benefit. To decide that, you weigh how infrequently and irregularly similar benefits are given, their total value, and how hard they are to value. The limit applies to each benefit for each person — it isn't an annual allowance — and associates' benefits are tested separately. Go over the limit and the whole value is taxable; there's no partial exemption.
The classic small business use is the end-of-year function and gifts. A Christmas lunch at a restaurant costing A$180 a head, held once a year, is typically an exempt minor benefit for each attendee. A separate A$150 gift voucher given at the same time is assessed on its own, so it too can be minor. The catch: entertainment benefits that are exempt minor benefits aren't income tax deductible and carry no GST credits.
Car parking
A car parking benefit can arise when you provide parking at or near the workplace and a commercial car park within one kilometre charges more than the car parking threshold of A$11.48 a day for all-day parking. Small businesses with aggregated turnover under A$50 million are generally exempt, provided the parking isn't at a commercial car park. Most suburban and regional small employers therefore pay no FBT on staff parking.
The FBT calendar for the 2027 FBT year
1 April 2026
FBT year starts; EV home charging rate rises to 5.47 c/km
Quarterly BAS
FBT instalments if last year's FBT was A$3,000 or more
31 March 2027
FBT year ends; last day of the full EV exemption under current policy
1 April 2027
Proposed EV changes start (if legislated)
21 May 2027
Lodge and pay FBT (25 June via a tax agent)
14 July 2027
STP finalisation including reportable fringe benefits
Common FBT mistakes and how they get fixed
Ignoring the director's car. A company that gives its owner-director a car creates a car fringe benefit, even if the director is the only employee. Fix: register for FBT, keep a logbook, or have the director make an after-tax contribution to reduce the taxable value.
No logbook. Without a valid 12-week logbook, the operating cost method treats private use as 100%. Fix: keep a logbook in the first year the car is provided, and refresh it at least every five years or when use changes.
Treating EVs as "nothing to do". Exempt EVs still need a notional value worked out and reported. Fix: calculate reportable amounts for each employee and include them in your Single Touch Payroll finalisation by 14 July.
Assuming a PHEV is exempt. New PHEV arrangements from 1 April 2025 attract FBT. Fix: value the PHEV as a normal car and consider employee contributions.
Missing the record keeping concession. If your aggregate fringe benefits are small — under the record keeping exemption threshold of A$10,962 for the 2027 FBT year — and you meet the other conditions, you may be able to base your FBT on a past year's records instead of keeping full records each year. Check eligibility with the ATO before relying on it.
Official links
- ATO — FBT rates and thresholdsRate, gross-ups, car parking threshold, benchmark rate
- ATO — Electric cars exemptionEligibility, PHEVs, reporting
- ATO — Lodging your FBT return and payingDue dates and instalments
- Treasury — EV FBT consultationProposed changes from 1 April 2027
- ATO — Luxury car tax rate and thresholdsFuel-efficient threshold used in the EV test
What to do next
List every non-cash benefit your business gave employees and directors since 1 April 2026, decide which are exempt, and value the rest — cars first, because they're usually the largest. If you employ staff, check that your PAYG withholding and super guarantee setup handles reportable fringe benefits, and keep an eye on the EV bill before any new lease that starts after 31 March 2027.
This is general information, not legal or tax advice — confirm on the official source or with a professional.
Frequently asked questions
The FBT rate is 47% for the FBT year from 1 April 2026 to 31 March 2027, the same rate that has applied since the year ending 31 March 2023. It matches the top personal tax rate plus the Medicare levy. FBT is worked out on the grossed-up taxable value of benefits, not their cost, so the effective charge on the cost of a benefit is higher than 47%.
The FBT year runs from 1 April to 31 March, not the 1 July financial year. The current FBT year started on 1 April 2026 and ends on 31 March 2027. If you self-lodge, the return and payment are due by 21 May; if a tax agent lodges electronically and you were on their client list by 21 May, the due date is generally 25 June.
Yes, for now. An eligible battery or hydrogen fuel cell electric car first held and used from 1 July 2022, priced below the luxury car tax threshold for fuel-efficient vehicles, is exempt from FBT. The government has announced that from 1 April 2027 the full exemption would apply only to EVs costing A$75,000 or less, with a 25% discount above that. That change is not yet law and existing leases are protected.
Not for new arrangements. From 1 April 2025 a plug-in hybrid is no longer a zero or low emissions vehicle for FBT purposes. A plug-in hybrid can keep the exemption only if it was already being provided under the exemption before 1 April 2025 and the employer has a financially binding commitment to keep providing it for private use on and after that date.
A benefit is exempt as a minor benefit if its notional taxable value is less than A$300 and it would be unreasonable to treat it as a fringe benefit, considering how often and regularly similar benefits are given and their total value. The limit applies per benefit, per employee — it isn't an annual allowance — and going over it means the whole amount is taxable.
A sole trader doesn't pay FBT on benefits they take for themselves, because they aren't their own employee. They do pay FBT if they provide fringe benefits to employees or their associates. Company directors are different: a director who receives benefits from their company is an employee for FBT purposes, so the company may owe FBT.
Sources & verification
Figures on this page were checked against the sources below when it was last reviewed on 9 October 2026. Each rate and limit is stored once with its own official source and review date, and official update channels are monitored daily so changes are picked up. How we verify
- 1.Fringe benefits tax – rates and thresholds — Australian Taxation Office · accessed 9 October 2026
- 2.Electric cars exemption — Australian Taxation Office · accessed 9 October 2026
- 3.Fairer tax treatment to encourage affordable EVs — The Treasury (Treasurer's office) · accessed 9 October 2026
- 4.Sustainable fringe benefits tax treatment of electric cars — The Treasury · accessed 9 October 2026
- 5.Australian Customs Notice No. 2026/19 — Luxury Car Tax thresholds for 2026-27 — Australian Border Force · accessed 9 October 2026
- 6.Fringe Benefits Tax Assessment Act 1986 — section 58P (minor benefits) — AustLII (consolidated Commonwealth legislation) · accessed 9 October 2026
- 7.Lodging your FBT return and paying — Australian Taxation Office · accessed 9 October 2026
- 8.Removal of FBT exemption for electric vehicles — Grant Thornton Australia · accessed 9 October 2026
MSMETOOLS is an independent platform and is not affiliated with any government agency, ministry or department.
Tools for this
Salary Slip Generator
Create professional salary slips in seconds.
Budget Planner
Plan and track your business budget easily.
Related guides
 PAYG Withholding 2026: Tax Tables & How to CalculateRead guide
 Small Business CGT Concessions 2026: The 4 Rules ExplainedRead guide
 TPAR 2026: Who Lodges, 28 August Due Date & PenaltiesRead guide
 How to Pay Yourself as a Company Director in Australia 2026Read guide
Official links open the government site in a new tab.